FINANCIAL INFRASTRUCTURE INTELLIGENCE
Financial Infrastructure Foundations and Practice
Understanding Financial Management. Applying It to Organizational Requirements.
This collection helps organizational leaders understand how financial responsibilities, systems, workflows, controls, and executive oversight work together. Through foundational analysis, practical examples, and evaluation frameworks, it examines how to assess financial management arrangements, address structural weaknesses, and sustain reliable reporting, accountable oversight, and operational continuity.
-
Financial Infrastructure Intelligence · By Syndia Alexandre, Founder & CEO
Financial management arrangements should be evaluated against the responsibilities an organization requires—not simply the services a provider advertises. This guide distinguishes financial responsibilities from their supporting infrastructure and provides a framework for evaluating professional capabilities, coordination, and accountability.
Financial Management Responsibilities
Financial management connects financial execution with the information, controls, planning, and leadership required to manage organizational resources.
Accounting establishes the financial record through transaction processing, reconciliations, financial close, and financial statement preparation. Controller oversight supports accounting quality, reporting integrity, documented policies, and internal controls. Financial planning connects historical performance with budgets, forecasts, cash expectations, and resource decisions. Executive financial leadership interprets these conditions in the context of organizational priorities.
These responsibilities are related but not interchangeable.
Accurate accounting does not automatically establish effective planning. A forecast does not resolve incomplete records. Executive advice does not, by itself, ensure that transactions, reconciliations, and reporting are completed reliably.
Leadership should therefore identify both the responsibilities required and the arrangements connecting them. The relevant question is not simply whether financial work is being completed, but whether it is appropriately executed, reviewed, coordinated, and sustained.
Financial Infrastructure and Organizational Requirements
Financial infrastructure is the environment through which financial responsibilities operate. It includes systems, workflows, responsibilities, approval authority, controls, documentation, reporting structures, and oversight arrangements.
Infrastructure requirements depend on the organization’s activities and obligations. Additional entities, programs, funding sources, locations, and contractual commitments may change how financial work must be performed and reviewed.
Revenue and employee count provide context, but they do not independently define complexity.
A useful evaluation begins with questions such as:
What financial information does leadership require?
What obligations must the organization fulfill?
Which activities require authorization, documentation, or specialized review?
Where do processes depend on individuals?
Which existing arrangements function reliably?
The objective is not to introduce more infrastructure than necessary. It is to establish an environment appropriate to the responsibilities the organization must fulfill.
Accounting, Controller, CFO, and Integrated Service Models
Financial service labels describe general areas of emphasis. Actual responsibilities depend on the provider and engagement agreement.
Bookkeeping and outsourced accounting commonly address financial records, reconciliations, close procedures, and reporting. Controller services generally emphasize accounting supervision, reporting integrity, policies, and controls. CFO engagements may emphasize planning, forecasting, analysis, resource allocation, and executive decision support.
Some providers combine these responsibilities. Others concentrate on a narrower scope.
Integrated financial management connects execution, review, operations, and executive leadership within a coordinated arrangement. Its defining feature is not the number of advertised services, but how responsibilities work together.
Remote delivery describes how services are provided; it does not establish scope or availability. Likewise, a fractional title does not fully explain what a provider will perform.
Evaluation should move beyond labels to documented responsibilities, deliverables, coordination procedures, and accountability.
Scope, Coordination, and Accountability
A financial management engagement should make three matters clear.
First, scope: what will the provider perform, review, or coordinate? What remains with employees, leadership, or external specialists?
Second, coordination: how will information move through transaction processing, reconciliation, close, reporting, analysis, and decision-making? Who resolves missing information and exceptions?
Third, accountability: who is responsible when required work is incomplete, deadlines are missed, or controls do not operate as intended?
These matters should be reflected in both the engagement agreement and operating procedures.
An arrangement can include capable professionals yet remain fragmented if handoffs are unclear. Similarly, a comprehensive service list can conceal responsibilities that no party has explicitly assumed.
A practical evaluation asks the provider to explain how a recurring financial process operates from beginning to end, including review, escalation, and leadership communication.
Provider Fit, Engagement Terms, and Professional Boundaries
The appropriate provider is the one whose capabilities and commitments correspond to organizational requirements.
A targeted accounting engagement may be sufficient where internal leadership manages planning, controls, treasury, and oversight. Broader support may be appropriate where responsibilities are fragmented or required capabilities are unavailable internally.
Before proceeding, clarify:
Scope and expected outputs.
Client responsibilities and information requirements.
Executive access and communication arrangements.
Pricing, exclusions, and adjustment provisions.
Continuity and transition arrangements.
Required specialized professionals.
Termination and information-transfer procedures.
Distinguish financial management from independent assurance and other specialized services. Preparing records and supporting an audit are different from issuing an independent audit opinion.
A suitable engagement does not assume every responsibility must move externally. It establishes who will fulfill each requirement and how the overall arrangement will remain accountable.
Infrastructure Strain, Alignment, and Scalability
-
Financial Infrastructure Intelligence · By Syndia Alexandre, Founder & CEO
Financial processes can become harder to sustain as organizational requirements change. This guide examines how strain develops, why visible symptoms require investigation, and how alignment connects financial responsibilities with the environment needed to support them.
Recognizing Infrastructure Strain
Infrastructure strain becomes visible when established financial arrangements struggle to support current requirements.
Indicators may include delayed close procedures, recurring reconciliations, inconsistent reports, unclear approvals, duplicated work, and dependence on individual employees.
No single indicator establishes a structural problem. An unusual reporting delay may reflect a temporary event. Repeated delays across several processes warrant a broader examination.
Leadership should consider both performance and the effort required to maintain it. Reports may arrive on schedule only because employees work excessive hours or reconstruct information outside established systems.
The question is not merely whether the financial environment continues operating. It is whether operations remain reliable, appropriately controlled, and sustainable under current conditions.
Distinguishing Symptoms from Underlying Causes
Similar symptoms can arise from different conditions.
A delayed close may result from missing documents, insufficient capacity, unresolved reconciliations, unclear review responsibilities, or disconnected systems. Repeated reporting corrections may reflect classification errors, inconsistent definitions, or inadequate validation.
Selecting an intervention before establishing the cause can preserve the underlying weakness.
Investigation should identify:
Where work stops or requires correction.
What information or authorization is missing.
Which responsibilities are unclear.
Whether the problem is recurring.
How existing systems and procedures contribute.
Additional personnel may be appropriate when capacity is insufficient. Technology changes may be warranted when current tools cannot support verified requirements. Process redesign may be necessary when coordination is the constraint.
Several interventions may be required together. Their selection should follow findings rather than assumptions.
How Workarounds Become Operating Dependencies
A workaround can be a reasonable response to an immediate limitation. The concern arises when the organization relies on it without appropriate documentation, ownership, review, or continuity arrangements.
Kontab Advisory uses three descriptive conditions to examine this progression.
Absorption occurs when individuals compensate for limitations through additional effort.
Adaptation occurs when those compensating activities become recurring operating practices.
Exposure occurs when a new demand or disruption reveals the dependency—for example, when an employee leaves or supporting information must be produced.
These conditions are analytical descriptions, not mandatory stages.
Leadership should distinguish controlled manual procedures from unmanaged dependencies. A documented spreadsheet with defined inputs and review may be appropriate. An unexplained spreadsheet that only one person can maintain presents a different issue.
The objective is not to eliminate every workaround. It is to determine which arrangements should be retained, formalized, redesigned, or replaced.
Connecting Reporting, Governance, and Operations
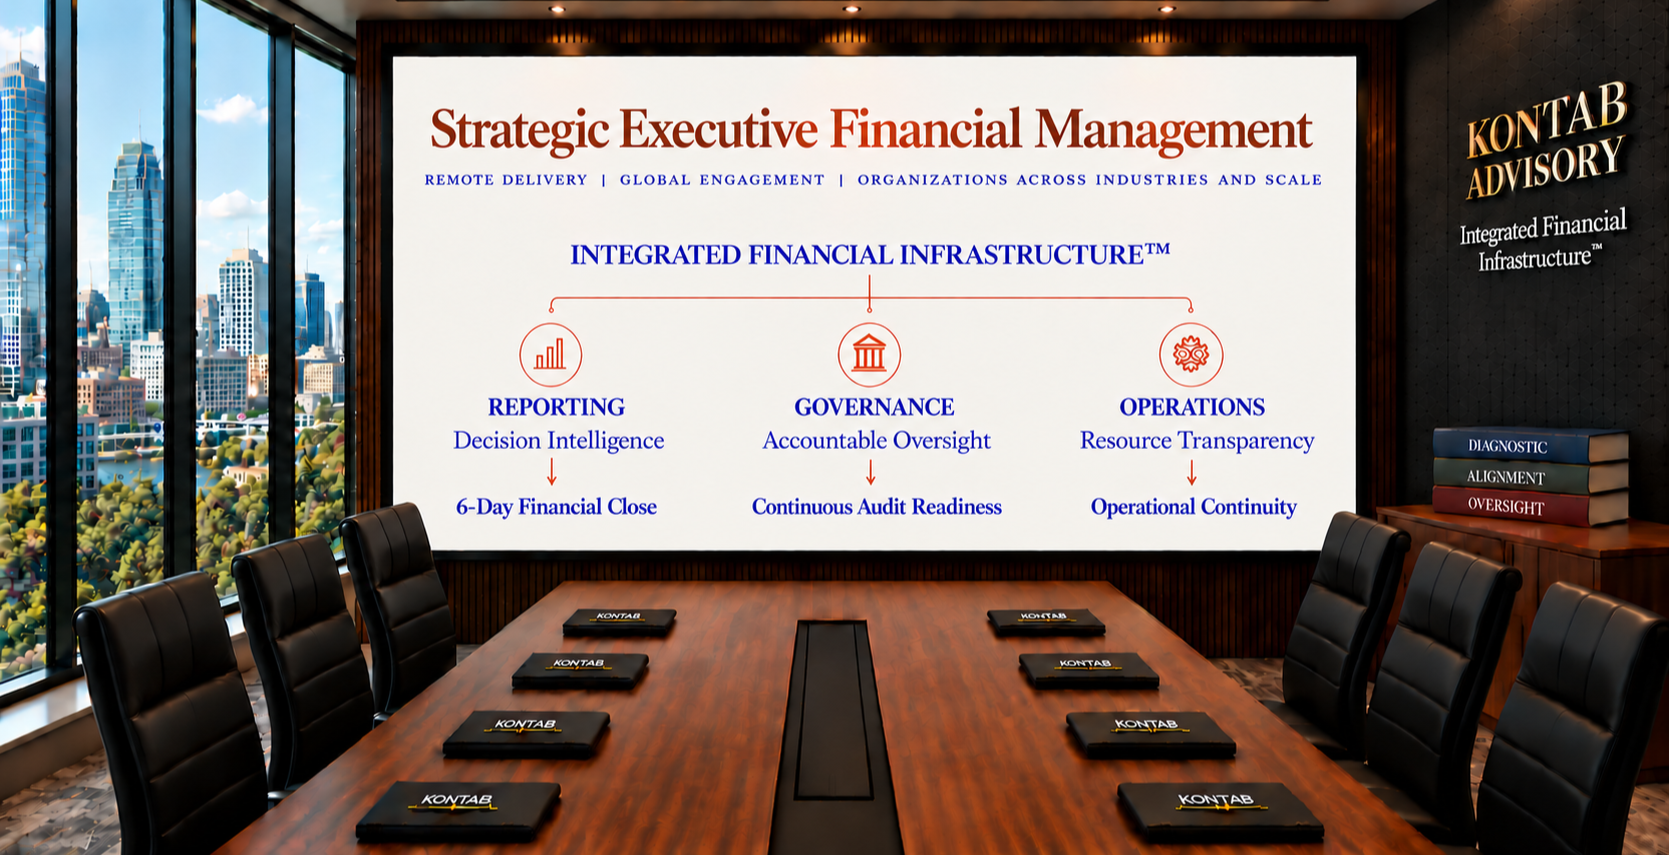
Reporting, governance, and operations perform distinct responsibilities within one financial environment.
Reporting transforms financial activity into information for analysis and decisions.
Governance establishes authority, controls, responsibilities, and oversight.
Operations execute transactions, coordinate resources, maintain workflows, and support continuity.
Their effectiveness depends on their relationships. Reliable reporting requires complete and appropriately recorded activity. Controls must operate where financial decisions and transactions occur. Operational procedures must support both execution and verification.
Alignment establishes these connections through defined responsibilities, consistent information, appropriate systems, and review procedures.
It does not require one software platform or identical procedures across every activity. It requires arrangements that work together and preserve necessary distinctions.
Structural Alignment in Practice
Consider a vendor invoice.
A coordinated workflow begins with receiving the invoice and required supporting information. The transaction is reviewed against relevant authorization, contract, budget, and funding requirements. A designated individual approves it within established authority.
The invoice then moves through accounting and payment procedures. Supporting records are retained, activity is reconciled, and the financial effect becomes available for reporting.
Exceptions require identified ownership throughout the process.
This example is illustrative, not a universal configuration. Appropriate procedures depend on the organization and transaction.
Its significance is the connection among execution, authorization, records, reconciliation, and reporting. A transaction should not become disconnected from its supporting evidence or accountability as it moves between people and systems.
Evaluating Automation Readiness
Automation should support an understood process.
Before implementation, determine whether:
Activities, inputs, outputs, and exceptions are defined.
Source information and classifications are reliable.
Authorization and review responsibilities are clear.
Appropriate validation and monitoring exist.
Configurations, maintenance, and continuity are documented.
Automation can reproduce incorrect rules as consistently as correct ones. It can also shift dependency from the person performing a process to the person maintaining its configuration.
Testing should include representative activity, unusual transactions, failures, and recovery procedures.
Measure more than speed. Consider error rates, exception volumes, reconciliation differences, correction effort, and ongoing maintenance.
The appropriate objective is dependable execution with suitable controls—not automation for its own sake.
Infrastructure Maturity and Ongoing Stewardship
-
Financial Infrastructure Intelligence · By Syndia Alexandre, Founder & CEO
Establishing a reliable financial environment is not the end of the work. This guide examines how oversight, review, and adaptation sustain financial management as organizational requirements evolve.
Understanding Financial Infrastructure Maturity
Financial infrastructure maturity describes how reliably the financial environment supports organizational requirements.
It is not determined solely by technology, staffing, automation, or organizational size.
A mature arrangement connects responsibilities with appropriate procedures, controls, information, and oversight. Its effectiveness can be demonstrated through dependable execution and the ability to maintain that execution as conditions change.
Maturity should therefore be evaluated in context.
An organization may require simple but well-controlled processes. Another may require extensive coordination across programs, entities, and funding structures.
The standard is not maximum sophistication. It is an appropriate environment that performs reliably and can be sustained.
Fragmented, Developing, Aligned, and Strategic Conditions
Kontab Advisory uses four descriptive conditions to discuss financial infrastructure maturity.
Fragmented environments rely heavily on disconnected processes and individual intervention.
Developing environments have increasingly standardized procedures and responsibilities, but coordination remains incomplete.
Aligned environments connect financial functions through established workflows, controls, reporting, and accountability.
Strategic environments use that reliable foundation to support forward-looking planning and proactive resource decisions.
These descriptions are not independently validated scores or a mandatory progression. Different functions within the same organization may demonstrate different conditions.
Their purpose is to support discussion: what works reliably, where dependencies remain, and what improvements organizational requirements justify.
Establishing an Appropriate Oversight Cadence
Oversight requires recurring opportunities to review performance and changing requirements.
The cadence should reflect the activity. Transaction exceptions may require immediate attention. Reconciliations and close procedures follow recurring schedules. Broader reviews of systems, responsibilities, and policies may occur periodically or when circumstances change.
An appropriate cadence identifies:
What is reviewed.
Who prepares and reviews the information.
What decisions or actions may follow.
How unresolved matters are tracked.
When issues require escalation.
Meetings alone do not establish oversight. Review must connect information with responsibility and follow-through.
The objective is sufficient attention at the appropriate time—not additional reporting without a clear purpose.
Recognizing Drift and Emerging Dependencies
Infrastructure drift occurs when established arrangements no longer reflect current activities or requirements.
Responsibilities may change without updated documentation. Reports may require increasing manual adjustment. Exceptions may become routine. New activities may be managed outside established systems.
These developments do not automatically require broad restructuring. They indicate a need to investigate.
Leadership should compare current practice with the arrangements previously established. Determine what changed, whether the change was intentional, and whether controls and responsibilities remain appropriate.
An early warning is often increasing effort rather than outright failure.
Recognizing that change creates an opportunity to address a limited weakness before it becomes embedded across several processes.
Adapting Responsibilities, Controls, and Reporting
Organizational change should prompt evaluation of its financial implications.
A new program may require different reporting. A new funding source may introduce documentation obligations. A leadership transition may alter approval authority. A system change may affect access, reconciliation, or exception handling.
Adaptation should connect these requirements rather than address each in isolation.
Define the change, identify affected processes, assign responsibility, update documentation, and verify that the revised arrangement works.
Preserve what remains effective. Not every change requires new software, additional staffing, or a complete redesign.
Appropriate adaptation maintains continuity while bringing the financial environment into alignment with current requirements.
Sustaining Organizational Stewardship
Stewardship concerns the responsible management, protection, and allocation of organizational resources.
Financial infrastructure supports stewardship by providing dependable information, accountable authority, and reliable execution.
Leadership remains responsible for judgment and organizational decisions. Infrastructure does not replace that responsibility; it helps make relevant conditions visible and supports implementation.
Sustained stewardship requires attention to current obligations and future requirements. Reporting explains what has occurred. Planning examines what may follow. Controls govern activity. Operations carry out decisions.
When these responsibilities remain connected, leadership is better positioned to evaluate commitments, respond to change, and maintain continuity.
Structuring Financial Responsibilities and Leadership Continuity
-
Financial Infrastructure Intelligence · By Syndia Alexandre, Founder & CEO
Financial responsibilities may be fulfilled by internal employees, external partners, organizational leadership, and specialized professionals. This guide examines how to structure those relationships without leaving gaps in execution, authority, or continuity.
Hiring Internally, Outsourcing, or Combining Both
Selecting a delivery model begins with identifying required responsibilities and existing capabilities.
An internal hire may provide dedicated organizational presence and capacity. Outsourcing may provide defined capabilities or broader coordinated support. A combined arrangement may preserve internal knowledge while adding review, specialization, or leadership.
None is universally preferable.
Compare options against scope, required availability, supervision, coverage, implementation demands, and retained responsibilities. Evaluate the full arrangement rather than comparing a salary with a provider’s fee alone.
A suitable model explains how execution, review, planning, and executive oversight will operate together.
The decision should follow organizational requirements—not an assumption that one model is inherently more efficient.
Working Alongside an Existing Accounting Team
External financial management does not necessarily require replacing internal personnel.
Existing employees may hold valuable knowledge and perform important responsibilities reliably. The task is to determine how their work connects with additional capacity, review, controls, and leadership.
Begin by documenting current responsibilities and handoffs. Identify gaps, duplication, bottlenecks, and activities requiring different expertise.
Then establish who performs, reviews, approves, and coordinates each responsibility.
Employees should understand where to obtain guidance and how exceptions are resolved. Leadership should understand which responsibilities remain internal.
The arrangement should strengthen the financial environment rather than create parallel teams operating with different assumptions.
Defining Execution, Review, Approval, and Escalation
These responsibilities should be distinguished.
Execution completes the activity.
Review evaluates completeness, accuracy, or compliance with established procedures.
Approval authorizes an action within defined authority.
Escalation brings an exception or consequential decision to the appropriate level.
Assigning them clearly helps prevent assumptions that one person or provider is responsible for everything associated with a transaction.
Where feasible, incompatible responsibilities should be separated. Where staffing limits separation, evaluate appropriate supervisory or compensating review arrangements.
Document thresholds, required evidence, deadlines, and exception ownership.
The objective is not a complicated responsibility chart. It is an arrangement people can follow and leadership can oversee.
Preparing for Finance Leadership Transitions
A transition should begin with continuity.
Identify upcoming payments, payroll requirements, reporting deadlines, funding obligations, close activities, and unresolved matters.
Confirm access to systems, banking information, records, and supporting documentation through authorized procedures. Review approval authority and update access when responsibilities change.
Assign interim ownership and escalation arrangements. Communicate relevant changes to employees and external professionals.
Distinguish immediate continuity needs from longer-term improvements.
A transition may reveal structural weaknesses, but attempting a comprehensive redesign before essential responsibilities are secured can create unnecessary disruption.
Preserving Institutional Knowledge and Process Continuity
Documentation should allow an appropriately qualified person to understand and continue required work.
Useful records explain purpose, timing, inputs, responsibilities, system interactions, review, and exception handling.
A list of tasks may be insufficient if the underlying decisions remain undocumented. Conversely, extensive manuals provide limited value when outdated or inaccessible.
Prioritize critical recurring activities and known dependencies.
Test continuity arrangements through practical review: can another authorized person locate the information, understand the procedure, and identify when professional judgment is required?
Knowledge transfer should preserve both the process and the context needed to perform it responsibly.
Coordinating Specialized Professionals
Some responsibilities require separate expertise, authorization, or independence.
The financial management arrangement should identify when tax, legal, assurance, valuation, or other specialized support is required.
Clarify who engages the professional, supplies information, tracks requests, reviews management responses, and implements agreed actions.
Coordination does not transfer every professional responsibility to the coordinator.
Independent auditors, for example, retain responsibility for their assurance work, while management remains responsible for its records, representations, and decisions.
Clear boundaries reduce duplication and prevent important matters from falling between providers.
Managing Financial Complexity Across Funding, Programs, and Entities
-
Financial Infrastructure Intelligence · By Syndia Alexandre, Founder & CEO
Complexity arises when activities carry different financial, operational, or reporting requirements. This guide examines how to preserve those distinctions while producing coordinated information and execution.
Identifying Financial and Operational Requirements
Begin by mapping the organization’s activities and obligations.
Relevant dimensions may include entities, programs, locations, funding arrangements, contracts, stakeholders, systems, and reporting deadlines.
Determine which distinctions must remain visible in records and reports. Identify who owns the information and how it enters the financial environment.
Do not assume that organizational labels establish identical requirements. Two grants or contracts may impose different conditions.
A requirements map provides the basis for coding, documentation, controls, reporting, and responsibility assignments.
Its value lies in connecting obligations to daily execution rather than maintaining a separate list that financial processes do not reflect.
Managing Restricted Funding and Multiple Programs
Restricted funding requires financial activity to be evaluated against the applicable terms and accounting requirements.
Donor restrictions, grant conditions, and contractual obligations should not be treated as interchangeable.
Establish how relevant activity is identified, recorded, supported, reviewed, and reported. Determine whether allocation methods are appropriate and documented.
Connect program budgets and funding schedules with accounting records. Investigate differences rather than maintaining unreconciled versions of performance.
Cash held does not, by itself, establish that resources are available for every expenditure.
Leadership needs information that distinguishes financial position, funding availability, outstanding obligations, and future resource requirements.
Coordinating Multiple Entities and Locations
Multiple entities and locations require clarity about what is separate and what is shared.
Each entity may have distinct records, obligations, banking arrangements, and approval requirements. Locations may operate within one entity while requiring separate operational visibility.
Define reporting dimensions, shared deadlines, account definitions, and responsibility assignments.
Inter-entity activity and shared expenses require appropriate identification, support, and reconciliation. The applicable structure and accounting requirements determine whether and how consolidated information is prepared.
Leadership visibility should not obscure entity-level accountability.
Coordination means producing useful overall information while preserving the distinctions necessary for accurate records and oversight.
Establishing Responsibilities Across Distributed Teams
Distributed operations require dependable information flow and clearly assigned authority.
Define how source documents are submitted, who validates them, where approvals occur, and how incomplete information is resolved.
Establish common procedures where appropriate while documenting justified local differences.
Time zones, system access, staff availability, and local obligations may affect deadlines and handoffs.
Exceptions should have identified owners rather than circulate among teams without resolution.
Remote coordination works through accessible records, documented responsibilities, consistent communication, and reliable follow-through—not simply more frequent meetings.
Connecting Cash Availability, Funding Limitations, and Commitments
Financial performance, cash held, available funding, and payment obligations describe different aspects of the organization’s condition.
A useful cash outlook connects expected receipts, payment timing, contractual commitments, funding limitations, and management assumptions.
Distinguish confirmed information from estimates. Update assumptions when conditions change.
Where resources cannot be used for every purpose, leadership needs visibility into those limitations alongside total balances.
The objective is to understand what resources are expected, what obligations must be met, and where timing or availability may create pressure.
A forecast supports judgment; it does not eliminate uncertainty.
Producing Coordinated Leadership Information
Leadership reporting should connect relevant views without creating competing versions of the financial position.
Define common reporting periods, classifications, assumptions, and reconciliation procedures.
Provide entity, program, location, or funding views where they support decisions. Explain how those views relate to the underlying accounting records.
Highlight significant differences, commitments, limitations, and unresolved matters.
More detail is not automatically more useful. The reporting package should answer identifiable leadership questions and make important qualifications visible.
Coordinated information enables comparison while preserving context.
Financial Reporting, Board Oversight, and Audit Readiness
-
Financial Infrastructure Intelligence · By Syndia Alexandre, Founder & CEO
Financial reporting supports oversight when reliable records are translated into relevant information, reviewed appropriately, and connected with action. This guide examines that process and the documentation needed to support professional review.
Establishing Reliable Accounting and Close Procedures
Reliable reporting begins before reports are prepared.
Source information must be complete, transactions recorded appropriately, balances reconciled, and significant judgments reviewed.
A close process identifies required tasks, owners, reviewers, dependencies, and deadlines. It also defines how unresolved items are tracked and communicated.
Completion should reflect evidence that required work occurred—not merely that a checklist was marked finished.
The appropriate timeline depends on organizational requirements and the work necessary to produce dependable information.
Speed is useful when achieved through reliable processes, not deferred investigation or unsupported adjustments.
Designing Management and Board Reporting
Management and boards may require different levels of detail, but both need information appropriate to their responsibilities.
Management reporting may support operational decisions, budget monitoring, cash planning, and issue resolution.
Board reporting should support oversight of financial condition, significant obligations, resource decisions, and material risks.
Define what each audience needs to understand and what action may follow.
A useful package may combine financial statements, comparisons, forecasts, explanatory commentary, and decision items.
Avoid assuming that distributing statements alone establishes understanding. Information should be presented with sufficient context for its intended use.
Explaining Variances, Forecasts, and Financial Commitments
A variance identifies a difference. Analysis explains why it occurred and why it matters.
Distinguish timing differences from continuing changes. Identify whether the cause affects future expectations or requires action.
Forecasts should show their assumptions and relevant uncertainty. Commitments should be evaluated alongside recorded results so leadership understands obligations not fully conveyed by historical performance.
Explanations should be specific enough to support decisions without overwhelming the reader.
Where information remains incomplete, state the limitation and the plan for resolution.
Confidence in reporting depends partly on making uncertainty visible rather than presenting unsupported precision.
Connecting Reporting with Decisions and Follow-Up
Financial reporting should lead to appropriate review and action.
Separate information items, matters requiring investigation, and decisions requiring authorization.
For each consequential issue, identify the responsible person, required action, and expected timing.
Subsequent reporting should show whether the matter was resolved, remains open, or requires a revised response.
This creates continuity between reporting periods and prevents recurring concerns from being repeatedly acknowledged without progress.
Reports do not make decisions. They should equip the appropriate individuals to make them and provide a record of follow-through.
Maintaining Supporting Records and Audit Readiness
Audit readiness is supported by records and procedures maintained throughout ordinary operations.
Relevant materials may include reconciliations, supporting schedules, transaction evidence, approvals, agreements, accounting policies, and documentation of significant judgments.
Assign responsibility for preparation, review, retention, and retrieval.
Readiness does not mean every question has been anticipated. It means the organization can provide coherent records, explain its processes, and respond to requests without unnecessarily reconstructing routine information.
Preparing for professional review should remain connected to everyday accounting and controls rather than depend entirely on a year-end recovery effort.
Coordinating With Independent Auditors and Defining Professional Boundaries
Effective coordination establishes request ownership, deadlines, communication channels, and procedures for resolving outstanding matters.
The financial management team may prepare schedules, reconcile records, explain processes, and assist leadership in evaluating proposed adjustments.
Independent auditors retain responsibility for their audit procedures and conclusions. Management retains responsibility for the organization’s financial information, representations, and decisions.
Supporting audit readiness does not guarantee an audit opinion.
Kontab Advisory’s financial management role includes maintaining records and coordinating with independent professionals within the agreed scope. It does not include performing independent financial statement audits, reviews, or attestations.
Professional boundaries should remain explicit throughout the engagement.
Financial Infrastructure Intelligence presents professional analysis and Kontab Advisory’s applied methodology. Illustrative examples and descriptive frameworks are not independently validated diagnostic scores, guarantees, or substitutes for evaluating an organization’s specific circumstances. Specialized accounting, tax, legal, contractual, and assurance matters require consideration of applicable requirements and appropriate professional expertise.