Article Description
CFO advisory connects financial reporting, planning, forecasting, liquidity, and resource evaluation with executive decision-making. This publication examines Executive Financial Leadership, including financial performance, capital commitments, governing-body reporting, organizational expansion, financial transitions, leadership continuity, and stewardship across internal and outsourced financial management arrangements.
Introduction
CFO advisory is a professional service arrangement through which financial analysis, planning, forecasting, capital evaluation, and executive recommendations inform organizational decisions. An engagement may provide ongoing financial leadership, periodic advice, or focused evaluation of a significant decision.
Responsibilities, deliverables, and decision rights must be explicit. Authorized executives and governing bodies retain authority for commitments, strategic approvals, and institutional accountability unless authority has been lawfully delegated under applicable governance arrangements.
Organizations engage CFO advisors to interpret financial conditions, evaluate commitments, strengthen planning, assess risks, and inform organizational direction. The value of this work depends on available evidence, reasonable assumptions, consideration of alternatives, and clear recommendations. Financial information informs decisions; it does not independently determine them.
How Does CFO Advisory Differ From Outsourced Accounting, Financial Operations, and Controllership?
Outsourced accounting performs defined accounting activities and maintains records. Financial operations management coordinates personnel, systems, authority, and workflows. Controllership emphasizes reliability, reporting integrity, controls, and accountability for unresolved matters. CFO advisory interprets financial conditions and evaluates alternatives involving resources, commitments, risks, and priorities.
These are principal service emphases, not exclusive responsibilities. A CFO advisor may coordinate accounting personnel, oversee reporting, participate in management, or contribute to controls within the engagement. An internal CFO may hold formal authority that an external advisor does not. The engagement and governance arrangements determine the responsibilities and authority assigned.
What Responsibilities Remain With Organizational Leadership?
Officers and governing bodies retain responsibility for decisions within their established authority. An advisor may evaluate options, explain risks, recommend action, and coordinate implementation within scope. Professional recommendations do not become organizational directives solely because of their origin.
Leadership should identify who approves commitments, implements authorized decisions, and evaluates subsequent performance. Clear boundaries preserve accountability while allowing appropriate professional support.
This publication examines Executive Financial Leadership: connecting financial understanding with priorities, resource commitments, operating capacity, and decisions. Execution performs activities and maintains records; Management coordinates personnel, systems, and authority; Oversight evaluates reliability and exceptions; Leadership interprets information, limitations, and implications.
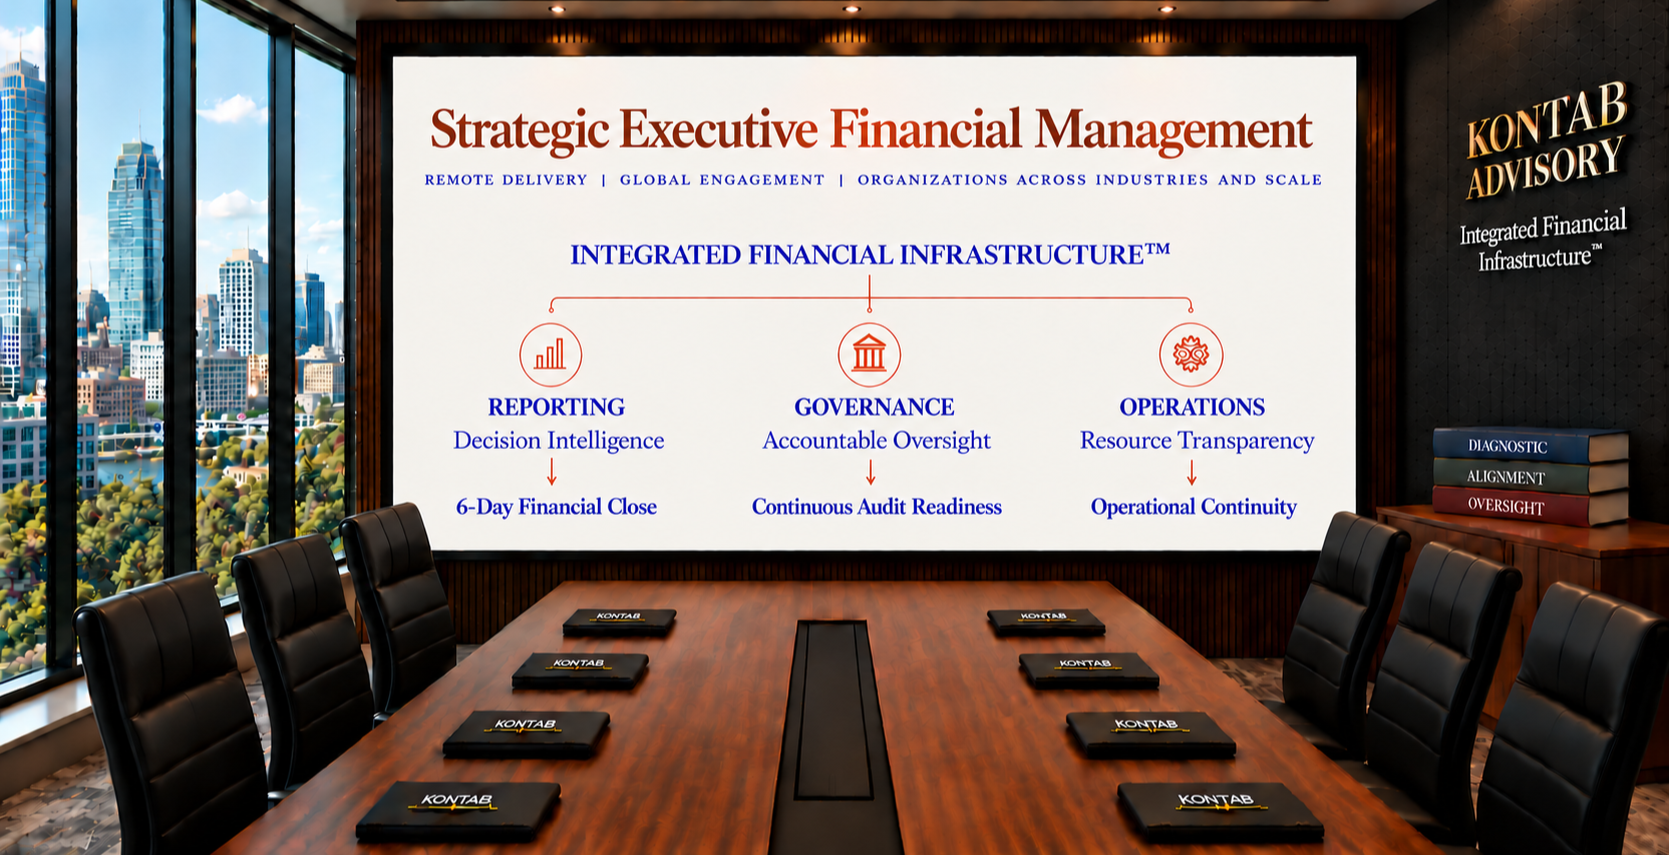
These responsibilities operate concurrently across Financial Accounting, Financial Operations, Financial Governance, and Financial Reporting. Integrated Financial Infrastructure™ is Kontab Advisory's coordinating methodology; Diagnose → Align → Sustain describes its professional engagement progression.
Executive Financial Leadership relies on dependable information, accountable operations, and oversight. It does not replace them.
Connecting Financial Information With Executive Decisions
Financial information becomes useful when it addresses a consequential organizational question. Statements show reported performance, budget comparisons reveal variances, and cash projections identify possible shortfalls. The response depends on causes, alternatives, obligations, and decision authority.
An advisory arrangement should identify supported decisions, available information, deliverables, reporting cadence, escalation requirements, and authorized decision-makers. Distinguish established facts from estimates, assumptions, professional judgments, and unresolved uncertainties.
Expenditure above budget does not independently establish a need for corrective action. Timing, increased demand, contractual changes, misclassification, or recurring cost increases may each call for different responses. Establish causes before recommending changes to staffing, services, financing, or commitments.
When information is incomplete, explain the limitation and its significance. Unsupported precision may obscure uncertainty rather than improve judgment.
A disciplined decision process connects:
Decision requirement: The question requiring action.
Financial evidence: Relevant records, results, obligations, and support.
Interpretation: Conditions explaining the information.
Assumptions and uncertainties: Estimates, gaps, and factors subject to change.
Available alternatives: Feasible responses within organizational constraints.
Tradeoffs: Financial, operational, contractual, and governance implications.
Recommendation: The proposed response and rationale.
Decision authority: The officer or governing body authorized to act.
Follow-through: Conditions and information requiring subsequent evaluation.
A recommendation is not authorization. Document reasoning proportionately: routine choices may need concise analysis, while major commitments may warrant a decision memorandum preserving evidence, assumptions, alternatives, and rationale. This supports later evaluation and leadership continuity.
Decision Memorandum Example
For a proposed service program, evaluate demand, staffing, technology, funding, cash timing, implementation capacity, and uncertainty. Accounting supplies the current position; Operations supplies cash and commitment information; Oversight identifies unresolved reporting, control, or compliance concerns.
Leadership integrates this evidence and compares launch dates, staffing arrangements, or implementation schedules. The authorized executive or governing body decides. Documented assumptions permit later evaluation without implying that the forecast guarantees an outcome.
Financial Planning and Performance Management
Planning connects objectives with resources, operating requirements, and commitments. Four related views serve different purposes:
Budget: An approved or intended plan for a defined period.
Forecast: Updated expectations based on current information and assumptions.
Scenario: Consequences of alternative conditions.
Actual results: Recorded activity under the applicable accounting basis.
A variance identifies a difference, not its cause. Determine whether it reflects timing, operating activity, changed assumptions, classification, or a continuing financial shift. A temporary difference may not warrant the response required by a structural cost increase.
Connect assumptions to operational drivers such as staffing, service demand, program activity, contract terms, funding schedules, unit costs, capacity, and implementation timing. Obtain credible inputs from those responsible for these activities.
Assign input preparation, validation, projection review, change authorization, and communication of significant developments. Departments outside finance should understand requirements and deadlines. Financial Leadership evaluates whether assumptions remain reasonable and plans support priorities.
Test less favorable conditions to identify when commitments remain supportable, become difficult to sustain, or require reconsideration. Scenarios make dependencies and decision points visible; they do not predict with certainty.
After authorization, compare actual results with planning assumptions, explain material departures, and determine whether forecasts, operations, or decisions need revision. Emphasize consequential information rather than transactional volume.
Forecast Sensitivity Example
Suppose a significant receivable is expected within 45 days. A downside scenario tests collection after 90 days while payroll and contractual payments remain unchanged. The resulting shortfall may require evaluation of available liquidity, discretionary spending timing, and other authorized responses.
A separate revenue-reduction scenario tests a different condition. Delayed collection may create temporary liquidity pressure; reduced recurring revenue may reveal a persistent imbalance. Distinguishing them supports appropriate decisions.
Cash Flow, Liquidity, and Financial Commitments
Liquidity concerns the ability to meet obligations when due. Performance, bank balances, funding availability, and commitments describe different aspects of financial condition. A favorable operating result does not establish timely cash availability, and a substantial balance may include restricted, designated, committed, or contractually constrained resources.
Evaluate usable resources against anticipated receipts, payments, restrictions, and commitments. A practical outlook identifies opening resources, collections, payroll, vendors, debt service, contractual obligations, capital expenditures, and other material movements. Distinguish confirmed amounts from estimates and expose uncertainty.
A rolling forecast can identify periods when obligations exceed resources. It requires current information, transparent assumptions, and coordination with treasury and payment personnel.
Operations maintains banking and payment workflows; Execution records transactions and obligations; Oversight evaluates supporting information and controls. Leadership interprets the results and recommends responses.
Distinguish temporary timing differences from continuing imbalances. Delayed reimbursement may require short-term cash arrangements, while recurring deficits may require reconsideration of funding, expenditure, or commitments.
Capital strategy adds repayment, financing costs, covenants, restrictions, and timing considerations. Borrowing may improve immediate liquidity while creating future obligations; equipment may reduce operating costs while consuming current resources. Evaluate affordability, terms, risks, and alternatives, distinguishing binding obligations from discretionary plans.
Financial leadership may evaluate financing within scope. Obtain specialized lending, investment, legal, tax, or other regulated advice from appropriately qualified professionals where required.
Liquidity and Commitments Illustration
An organization may report an annual surplus while payroll falls due before grant reimbursement. Both the favorable result and cash pressure may be accurate.
Evaluate unrestricted resources, reimbursement terms, collection timing, payroll, and other near-term commitments. A commitment schedule separates required payments from optional expenditure.
Recommendations may include postponing a purchase, revising implementation, or evaluating authorized financing. The decision depends on resources, obligations, and authority; accounting surplus does not eliminate cash-planning needs.
Supporting Management and Governing-Body Decisions
Operating management may need detailed program, staffing, cash, budget, contract, and exception information. A governing body may need a broader view of condition, obligations, commitments, risks, and formal approvals. Different detail should not produce inconsistent underlying information.
Decision-oriented reporting distinguishes:
Conditions requiring awareness.
Material differences requiring investigation.
Risks or obligations requiring attention.
Alternatives requiring evaluation.
Decisions requiring authorization.
Approved actions requiring follow-up.
Context matters: unfavorable variances are not always failures, and favorable results do not automatically establish strength. Reports should explain the question, evidence, assumptions, alternatives, tradeoffs, uncertainty, and deciding authority.
Distinguish management recommendations from governing-body decisions. An advisor may evaluate a facility commitment while management recommends it and the board approves it under applicable governance arrangements.
Preserve recommendations, approvals, implementation responsibilities, and follow-up through minutes, memoranda, and other appropriate records. Documentation must reflect actual authorization, not create its appearance.
Projected returns are only part of risk evaluation. Liquidity pressure, contracts, operational demands, and reporting obligations may alter a proposal's suitability. No single metric determines the preferred organizational course.
Decision Support and Governance
For a major lease, examine total contractual commitment, utilization, operating costs, cash requirements, relevant exit provisions, and sensitivity to lower revenue. Management may additionally need implementation budgets, staffing plans, and monthly projections.
Tailor reporting to each audience while retaining consistent assumptions. Explain tradeoffs and authorization requirements: an attractive model does not replace an authorized governance decision.
Evaluating Organizational Growth and Expansion
New programs, contracts, facilities, entities, locations, funding, or personnel may change records, authority, cash timing, reporting, and capacity. Evaluate both opportunity and the ability to sustain resulting commitments.
Assess benefits, implementation costs, recurring obligations, working capital, funding conditions, capacity, and uncertainty. Distinguish confirmed commitments from assumptions. An attractive long-term proposal may still strain near-term liquidity and operations.
Compare baseline and credible downside conditions, together with available responses. Test revenue timing, collection delays, staffing, startup costs, contracts, and minimum liquidity to identify supportability limits.
Readiness includes administrative requirements. Locations may need purchasing authority, reporting dimensions, payroll coordination, cash handling, and banking permissions. Funding may add restrictions, deadlines, and documentation; entities may require separate records, intercompany procedures, and specialist coordination.
Leadership identifies implications for the decision; Management coordinates arrangements; Execution performs work; Oversight evaluates reliability. These responsibilities remain concurrent during expansion.
“Infrastructure maturity precedes scalability” means dependable arrangements should support expanding requirements, not that growth is impossible until every system reaches a prescribed condition. Evaluate existing limitations, necessary improvements, and the sequence of commitments and infrastructure changes.
Distinguish manageable transition needs from structural gaps. Expansion does not automatically require software, additional finance personnel, or comprehensive redesign; responses should follow verified requirements and consequences.
Expansion Readiness Example
A second location may project favorable results after its first year while requiring deposits, staffing, reporting dimensions, purchasing authority, and treasury coordination before opening. Evaluate the timing of these commitments and administrative capacity.
A phased launch may reduce exposure while Management establishes workflows and Oversight evaluates reliability. The question is whether commitments and supporting arrangements remain appropriate under plausible conditions, not whether expansion looks desirable in isolation.
Financial Evaluation During Organizational Transitions
Leadership changes, restructuring, partnerships, acquisitions, conversions, and provider transitions can alter authority, information needs, and commitments. Define the particular decision and assigned scope: management review is not automatically comprehensive due diligence, valuation, or assurance.
Specify required evidence, covered periods and entities, assumptions, and limitations. Evaluation may involve results, records, liquidity, contracts, funding, commitments, related parties, unusual transactions, unresolved reconciliations, and documentation gaps.
Focus varies by transition. An acquisition may require historical performance, working-capital, contract, and integration analysis. Leadership succession may require pending decisions, access, authority, and planning assumptions. Conversion may require implementation costs, data integrity, and reporting continuity.
Distinguish information verified through agreed procedures from supplied information and estimates. Document limitations; do not represent incomplete information as independently verified.
Obtain legal, tax, valuation, regulatory, or assurance specialists as required. Financial professionals may coordinate records and evaluate operating consequences within their qualifications and engagement, not issue conclusions beyond them.
Protect payroll, payments, banking, close, funding reports, and approvals throughout transition. Management coordinates handoffs; Execution maintains work and records; Oversight evaluates reliability; Leadership compares alternatives and consequences.
Before broad changes, establish interim ownership, authority, escalation, essential activities, assumptions subject to revision, and information to preserve. Secure continuity before attempting comprehensive redesign.
Transition Evaluation Example
A replacement provider's fee is only part of the comparison. Include implementation, parallel operations, migration, temporary specialists, reporting delays, and record-transfer risk.
Management coordinates access and handoffs; Execution preserves records and recurring work; Oversight evaluates balances, controls, and reporting. Leadership compares dates and financial consequences, while the authorized decision-maker determines the arrangement using evidence and remaining uncertainty.
Maintaining Financial Leadership Continuity
Continuity preserves information, authority, and institutional understanding through change. It requires more than a successor or completed reports: accurate statements may not explain forecast assumptions, commitment rationale, or pending decisions.
Preserve essential context, including:
Plans and forecast assumptions.
Significant commitments and contracts.
Cash projections and funding conditions.
Decision memoranda and approvals.
Governing-body reporting materials.
Unresolved matters and pending decisions.
Specialist recommendations and limitations.
Follow-up ownership and escalation.
Documentation should reflect significance. Major commitments and uncertainties need more context than routine decisions, including reasoning, constraints, unresolved questions, and reconsideration triggers.
Continuity also requires operational capacity. Identify upcoming payroll, payments, close, funding, and reporting deadlines. Confirm authorized access to banking, systems, agreements, and records; reassign approval or review authority where appropriate; remove inappropriate access; communicate interim escalation.
A qualified, authorized successor should be able to understand the financial position and continue essential responsibilities. Secure these obligations before undertaking wider redesign, then evaluate targeted improvements and longer-term needs.
Institutional Memory Example
A new executive inherits a forecast showing a major cash increase in six months. Without assumptions, an estimate may be mistaken for confirmed funding.
Document whether it depends on an unsigned contract, estimated reimbursement, or confirmed schedule, including conditions affecting timing and amount. Accessible evidence and reasoning support appropriate revisions; preserving the spreadsheet alone does not establish continuity.
Executive Financial Stewardship
Stewardship concerns responsible evaluation, allocation, protection, and continuing management of resources in relation to institutional purpose and obligations. It considers evidence, capacity, stakeholders, and commitment consequences.
Reporting explains recorded results, planning evaluates expectations, governance establishes accountability, and operations administers resources. Leadership integrates these perspectives when considering priorities and decisions.
Stewardship does not maximize a single metric. Lower cost may increase continuity risk; projected growth may create obligations beyond current capacity. Make material tradeoffs and the conditions supporting recommendations visible.
Advisory work includes follow-through. Compare results with earlier assumptions, communicate material departures, and determine whether decisions need reconsideration. Preserve advice, authorization, and subsequent actions without transferring institutional responsibility to the advisor.
Funding, contracts, demand, personnel, and external conditions may change the suitability of commitments. Responses may include revised forecasts, implementation timing, allocations, or specialist advice, guided by current circumstances and authority.
Stewardship draws on Execution's evidence, Management's arrangements, and Oversight's reliability assessments. Leadership uses this combined understanding while acknowledging uncertainty.
Financial management supports continuity through dependable activities, accountable information, and responsible decisions; it does not independently guarantee continuity. Leadership contributes through transparent assumptions, informed choices, retained understanding, and subsequent evaluation.
Stewardship Under Uncertainty
Hiring approved on expected growth may remain appropriate despite a minor timing variance. A sustained revenue decline may require reconsideration of timing, funding, or other commitments.
Distinguish contractual obligations, alternatives, stakeholder effects, and authority. A recommendation may preserve the objective while adjusting timing or financing. It should reflect current evidence rather than rely indefinitely on earlier assumptions.
Conclusion
CFO advisory connects financial understanding with decisions, resource commitments, and continuity. Executive Financial Leadership interprets results, forecasts, liquidity, capacity, and uncertainty in relation to organizational priorities.
Its purpose is to inform authorized choices, expose material tradeoffs, and preserve the understanding needed to reconsider commitments. It depends on execution, management coordination, and oversight rather than replacing them.
Across Financial Accounting, Financial Operations, Financial Governance, and Financial Reporting, Leadership integrates evidence, interpretation, recommendations, and follow-through. Its effectiveness is demonstrated through informed decisions, transparent assumptions, accountable authority, and appropriate responses to changing conditions.
About Kontab Advisory
Kontab Advisory is a strategic executive financial management consultancy serving organizations across industries, disciplines, and scale. Integrated Financial Infrastructure™ is Kontab Advisory's proprietary methodology for coordinating financial reporting, governance, operations, and accounting across financial leadership, oversight, management, and execution.
The methodology aligns professional capabilities, systems, workflows, and accountability arrangements with organizational requirements to support organizational continuity.
Integrity by Design, Excellence by Standard.
This publication is intended for professional education and executive understanding. It does not constitute an independent audit, attestation, legal opinion, tax opinion, investment recommendation, or organization-specific professional engagement.