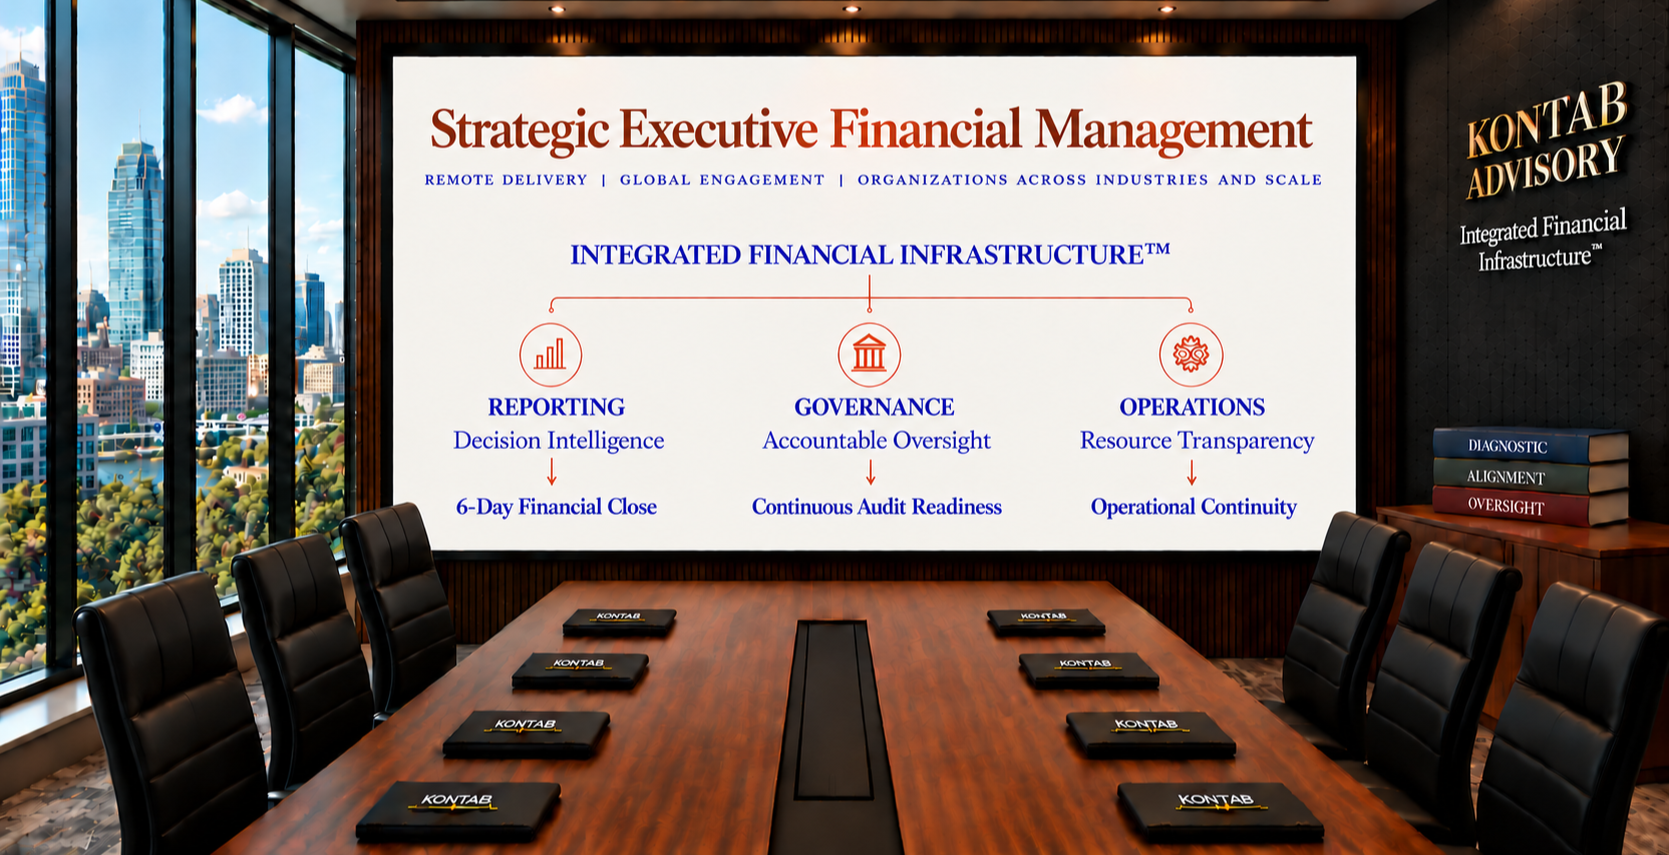
Executive Leadership
REPORTING · GOVERNANCE · OPERATIONS
15+
YEARS EXPERIENCE
$100M+
FINANCIAL OVERSIGHT
One Partner
INTEGRATED FINANCIAL INFRASTRUCTURE™
KONTAB ADVISORY
A Strategic Executive Financial Management Partner for Organizational Stewardship
Kontab Advisory is a strategic executive financial management consultancy serving organizations across industries, scale, and borders. We establish and manage the financial operating environment organizations require for reliable decision-making, accountable oversight, and operational continuity. Our methodology integrates financial responsibilities across reporting, governance, and operations—unifying accounting, controller oversight, treasury management, financial operations, and executive leadership within one strategic engagement.
We partner with nonprofits, associations, foundations, government entities, contractors, and corporations seeking stronger financial management or navigating growth, leadership transitions, complex funding, distributed operations, and evolving organizational requirements.
EXECUTIVE LEADERSHIP
The Experience Behind the Methodology
Syndia Alexandre | Founder & Chief Executive Officer
Syndia Alexandre brings more than 15 years of financial management experience and over $100 million in financial oversight across nonprofit, corporate, technology, education, and public accounting environments. Her experience spans accounting, financial reporting, budgeting, forecasting, treasury management, internal controls, compliance, and executive oversight across multi-program, distributed, and transitional operations. Across these environments, a recurring structural gap became evident: evolving organizational requirements frequently outpace financial infrastructure.
This observation informed the founding of Kontab Advisory and the development of Integrated Financial Infrastructure™—a methodology that aligns financial management responsibilities, systems, controls, and executive oversight with organizational requirements.
Infrastructure maturity precedes scalability.
INTEGRATED FINANCIAL INFRASTRUCTURE™
Organizational Requirements Determine Financial Infrastructure
Integrated Financial Infrastructure™ establishes a unified approach to organizational financial management through three interdependent functions:
Reporting — Decision Intelligence
Reliable financial information, timely reporting, and management analysis that support executive decision-making.
Governance — Accountable Oversight
Defined financial authority, internal controls, accountability, and oversight responsibilities that support organizational stewardship.
Operations — Resource Transparency
Coordinated financial workflows, treasury activities, systems, and operational responsibilities that sustain financial execution.
These interdependent functions establish the foundation for Kontab Advisory's professional standards, engagement execution, and ongoing institutional accountability.
THE KONTAB ADVISORY STANDARD
Integrity by Design, Excellence by Standard
Kontab Advisory maintains an integrated institutional standard governing professional responsibilities, engagement execution, organizational accountability, and executive stewardship.
Professional Standards
Disciplined Financial Management. Integrated Accountability.
Engagement Standards
Structured Execution. Ongoing Executive Oversight.
Institutional Credentials
Professional Identity. Defined Responsibilities.
Institutional Commitment
A Partner for Organizational Stewardship.
Evidence-Based Evaluation
Assess financial environments against verified organizational requirements to establish objective findings and recommendations.
Integrated Accountability
Coordinate accounting, controller oversight, financial planning, treasury management, reporting, and financial operations within one executive financial management engagement.
Operational Discipline
Establish defined responsibilities, documented workflows, internal controls, reliable reporting, and structured communication.
Executive Continuity
Sustain financial accountability through ongoing leadership engagement, financial oversight, and coordinated operations.
Financial Infrastructure Diagnostic
Evaluate the current financial environment against required infrastructure maturity to establish organizational requirements and objective engagement recommendations.
Financial Infrastructure Alignment
Align required organizational financial infrastructure based on diagnostic findings, integrating financial responsibilities, workflows, systems, and controls.
Financial Infrastructure Oversight
Sustain required organizational financial infrastructure through ongoing executive financial management across reporting, governance, and operations.
Engagement Structure
Deliver full-service, ongoing financial management based on organizational requirements rather than hourly billing, predetermined service packages, or fractional time allocations.
Executive Access
Maintain remote service delivery, direct executive involvement, and leadership meetings at least weekly.
Institutional Identity
Maryland-based strategic executive financial management consultancy serving organizations across industries, disciplines, scale, and borders; Maryland Limited Liability Company.
Industry Classifications
NAICS 541611 — Administrative Management and General Management Consulting Services; NAICS 541219 — Other Accounting Services.
Government Contracting
Unique Entity ID (UEI): TGV3TAXNVVH3; CAGE Code: 25UX9
Professional Accountability
Maintain defined engagement responsibilities, professional confidentiality, and coordination with organizational leadership, internal personnel, and external specialists.
Professional Boundaries
Support audit readiness and independent-auditor coordination without performing independent audits, reviews, or attestations. Integrate tax preparation into applicable ongoing client engagements without offering standalone tax services.
Executive Visibility
Establish reliable financial information and decision-ready reporting.
Governance Oversight
Sustain defined financial accountability, internal controls, and organizational stewardship.
Operational Continuity
Coordinate financial responsibilities, resources, systems, and workflows to support consistent execution.
Sustainable Scalability
Align financial infrastructure maturity with evolving organizational requirements.
Kontab Advisory enables organizational stewardship, strengthens operational continuity, and establishes sustainable scalability through Integrated Financial Infrastructure™.
FINANCIAL INFRASTRUCTURE INTELLIGENCE
Understanding the Structural Foundations of Financial Management
Financial Infrastructure Intelligence examines the organizational conditions that influence financial infrastructure maturity, reporting reliability, governance accountability, and operational continuity. Through practical analysis of financial management requirements, structural deficiencies, systems alignment, and institutional oversight, these resources provide a foundation for informed executive evaluation.
Understanding Financial Management, Infrastructure, and Provider Evaluation
Clarifying financial management responsibilities, infrastructure requirements, and the considerations that inform provider selection.
-
Understanding Financial Management, Infrastructure, and Provider Evaluation
Financial Infrastructure Intelligence Series · By Syndia Alexandre, Founder & CEO
Why understanding financial responsibilities, organizational infrastructure, and service model differences is essential to evaluating financial management providers.
Executive Analysis & Strategic Evaluation
Organizations depend on financial management to maintain accurate records, allocate resources, fulfill obligations, and support consequential decisions. Yet the term financial management is used to describe services with substantially different responsibilities, ranging from transactional accounting to executive financial leadership.
For organizational leaders, the challenge is not simply identifying which services are available. It is determining which financial responsibilities the organization requires, what infrastructure is necessary to sustain those responsibilities, and whether internal personnel and external providers can collectively manage the resulting financial environment.
These questions become more consequential as organizations expand, diversify funding, implement technology, assume additional contractual obligations, or navigate leadership transitions. Requirements can evolve faster than the systems, controls, responsibilities, and workflows supporting them.
Effective provider evaluation begins with understanding these relationships—not with comparing service lists.
Understanding Financial Management
Financial management encompasses the execution, coordination, analysis, and oversight of an organization's financial responsibilities. It connects financial activity with the reporting, controls, planning, and leadership required to manage organizational resources.
Accounting is foundational, but financial management extends beyond recordkeeping and financial statement preparation.
Accounting and Financial Reporting
Accounting establishes the financial record through transaction processing, bookkeeping, reconciliations, financial close, and financial statement preparation.
Reliable accounting supports an understanding of financial position, operating performance, cash flow, and applicable reporting obligations. However, accurate records alone do not establish whether information reaches leadership on time, receives sufficient analysis, or informs organizational decisions.
Controller Oversight and Internal Controls
Controller oversight generally addresses accounting supervision, financial reporting integrity, close management, accounting policies, internal controls, and audit readiness.
Recording a transaction is different from reviewing the processes, controls, and professional judgments governing it. Controller responsibilities connect accounting execution with the review and accountability needed to sustain reliable financial information.
Financial Planning and Executive Leadership
Executive financial management connects historical information with forward-looking organizational decisions.
Responsibilities may include budgeting, forecasting, cash-flow planning, treasury management, financial analysis, scenario evaluation, resource allocation, and executive decision support.
CFO-level leadership interprets financial conditions in the context of organizational priorities, operating requirements, risks, and strategic choices.
Integrated Financial Management
These responsibilities are interdependent.
Accounting establishes the financial record. Controller oversight supports the integrity of accounting processes, reporting, and controls. Financial planning interprets performance and anticipates resource requirements. Executive financial leadership connects information and analysis with organizational decisions.
When these responsibilities operate without sufficient coordination, organizations may experience reporting delays, inconsistent information, duplicated effort, and unclear accountability.
Integrated financial management connects execution, review, planning, and executive oversight within a coordinated operating environment. Its value lies in how responsibilities work together—not simply in how many services an engagement includes.
Understanding Financial Infrastructure
Financial infrastructure is the organizational environment through which financial responsibilities are assigned, executed, controlled, communicated, and sustained.
It includes systems, workflows, responsibilities, approval structures, internal controls, documentation, reporting arrangements, and governance.
Financial infrastructure is not synonymous with accounting software. An organization can use sophisticated technology while remaining dependent on manual workarounds, undocumented procedures, unclear approvals, or knowledge held by a single person.
Infrastructure maturity depends on whether these components collectively support organizational requirements.
Reporting — Decision Intelligence
Reporting infrastructure supports financial records, financial reporting, management analysis, and executive decision information.
Its effectiveness depends on the reliability, completeness, consistency, and timeliness of financial information, as well as its relevance to organizational decisions.
Weaknesses may appear through delayed financial close, recurring manual reconciliations, inconsistent reporting, or limited executive visibility.
Governance — Accountable Oversight
Governance infrastructure establishes financial authority, approval responsibilities, internal controls, accountability arrangements, and oversight procedures.
It connects financial activity and information with the organization's responsibilities and obligations.
Weaknesses may emerge when authority is unclear, responsibilities are insufficiently documented, controls are inconsistently applied, or oversight depends excessively on individual discretion.
Operations — Resource Transparency
Operational infrastructure supports transaction workflows, resource management, treasury activities, systems coordination, and operational continuity.
Its effectiveness depends on defined responsibilities, coordinated execution, appropriate systems, and dependable processes.
Weaknesses may appear through duplicated processing, fragmented workflows, resource visibility gaps, manual workarounds, or excessive personnel dependency.
The Structural Distinction
Financial management concerns the execution and oversight of financial responsibilities. Financial infrastructure establishes the environment through which those responsibilities operate.
The two are complementary but not interchangeable.
An organization may have qualified personnel and appropriate technology while continuing to experience structural deficiencies because its workflows, controls, responsibilities, and information are insufficiently aligned.
Alignment connects the financial responsibilities an organization requires with the environment needed to execute and sustain them.
Recognizing Organizational Requirements
Financial management requirements are shaped by an organization's operating environment—not by revenue or employee count alone.
A smaller organization managing restricted funding, government contracts, or multiple operating locations may face more demanding financial requirements than a larger organization with standardized activities and fewer reporting obligations.
Requirements must therefore be evaluated in context.
Growth and Expansion
Additional entities, programs, locations, and operating activities may increase transaction volumes, reporting demands, and coordination requirements.
Growth can expose limitations in existing close procedures, reporting structures, controls, systems, and responsibilities.
Funding and Contractual Obligations
Restricted resources, grants, government contracts, financing arrangements, and other agreements may introduce additional accounting, reporting, documentation, monitoring, and compliance responsibilities.
The applicable obligations—not the funding label alone—determine the financial capabilities and infrastructure required.
Leadership and Personnel Transitions
Personnel changes may expose undocumented procedures, concentrated institutional knowledge, unclear responsibilities, and weaknesses in operational continuity.
A process that functions only when a particular person is available may not provide the continuity the organization requires.
Systems Implementation and Automation
New technology may alter transaction flows, approvals, information exchange, reporting, and control responsibilities.
Implementation without sufficient process alignment can preserve or amplify existing deficiencies. Technology should support defined requirements rather than substitute for evaluating them.
Recognizing Strain Without Assuming the Cause
Delayed financial close, recurring manual reconciliations, inconsistent reporting, unclear approvals, and excessive personnel dependency may indicate that financial infrastructure is no longer aligned with organizational requirements.
These symptoms do not independently establish their causes.
A reporting delay, for example, may result from inadequate staffing, disconnected systems, missing documentation, unclear review responsibilities, or several conditions operating together.
Adding personnel or replacing software may be appropriate. However, selecting either intervention before evaluating the underlying environment risks addressing visible symptoms while preserving structural deficiencies.
An effective evaluation establishes what the organization requires, what currently operates reliably, where gaps or dependencies exist, and which additional capabilities or structural changes are justified.
Evaluating Financial Management Service Models
Financial management service providers vary in functional coverage, professional responsibilities, delivery arrangements, and engagement structures.
Providers may specialize in bookkeeping, outsourced accounting, controller services, fractional or virtual CFO services, or integrated executive financial management.
These categories provide useful distinctions, but titles alone do not establish what a provider will perform, oversee, or sustain.
Organizations should evaluate actual responsibilities and contractual commitments rather than relying exclusively on service labels.
Bookkeeping and Outsourced Accounting
Bookkeeping generally concentrates on transaction recording and financial record maintenance.
Outsourced accounting may encompass reconciliations, financial close, financial statement preparation, accounting supervision, and related reporting responsibilities.
These arrangements may be appropriate when an organization requires defined accounting functions and maintains sufficient internal capacity for broader financial management and executive oversight.
Evaluation should establish who remains responsible for planning, treasury, financial operations, internal controls, and executive leadership beyond the accounting scope.
Actual coverage depends on the provider and engagement agreement.
Controller Services
Controller services generally emphasize accounting oversight, reporting integrity, financial close, internal controls, accounting policies, and audit readiness.
These services may strengthen the reliability and accountability of existing accounting operations.
Some providers assume additional financial planning or operational responsibilities. Others maintain a narrower accounting and controls focus.
Organizations should determine whether the engagement addresses required responsibilities beyond controller oversight and how any remaining responsibilities will be fulfilled.
Fractional and Virtual CFO Services
Fractional CFO services generally provide executive financial expertise through part-time, allocated-time, or otherwise limited engagement arrangements.
Responsibilities commonly include financial planning, forecasting, cash-flow strategy, analysis, and executive advisory support.
Virtual CFO describes a remote delivery arrangement. It does not, by itself, establish service coverage, availability, or time commitment.
These models may be appropriate when an organization has reliable accounting processes and established financial infrastructure but requires additional executive financial expertise.
Where underlying reporting, execution, or infrastructure weaknesses exist, executive advisory support may need to be complemented by operational or structural capabilities.
Integrated Executive Financial Management
Integrated executive financial management unifies accounting, controller oversight, financial operations, treasury management, reporting, and CFO-level leadership within a single, coordinated financial management engagement.
Its purpose is to establish accountability for the relationships among financial functions rather than deliver multiple disconnected services.
This arrangement may be appropriate when organizational requirements call for coordinated financial execution, continuing executive oversight, and operational continuity across the financial environment.
The extent of integration should be demonstrated through defined responsibilities, connected workflows, review procedures, reporting arrangements, and ongoing accountability—not merely through the number of services advertised.
Engagement Structure
Financial management engagements may use hourly billing, project fees, recurring retainers, defined service packages, or comprehensive ongoing agreements.
The appropriate structure depends on the responsibilities required.
A discrete advisory assignment may warrant a limited engagement. Continuing financial execution and executive oversight may require an arrangement that supports regular access, coordination, accountability, and continuity.
The commercial structure should support the work—not determine the organization's requirements before they are understood.
Provider Evaluation Framework
Selecting an accounting consultant, outsourced CFO, controller, or comprehensive financial management provider requires more than comparing credentials, service descriptions, and fees.
Provider evaluation should begin with organizational requirements rather than a provider's standard service list.
Three dimensions provide a practical foundation: scope capacity, operational integration, and infrastructure context.
Scope Capacity
Can the provider execute and oversee the financial responsibilities the organization requires?
Evaluation should establish which functions the provider will perform, which remain internal, which require third-party expertise, and who is accountable for execution and review.
General familiarity with a function is not the same as contractual responsibility for performing or sustaining it.
Relevant responsibilities may include accounting, reporting, controller oversight, budgeting, forecasting, treasury management, financial operations, internal controls, audit readiness, and executive financial leadership.
The engagement should also establish who is responsible when deadlines are missed, information is incomplete, or controls fail.
Operational Integration
Can the provider coordinate interdependent responsibilities within a reliable financial environment?
Evaluation should determine how information moves from transaction processing through reconciliation, close, reporting, analysis, and executive review.
It should also establish how handoffs are managed, exceptions are resolved, issues are escalated, and leadership receives information.
The relevant question is not whether one provider offers several services. It is whether the arrangement connects those services into coordinated execution and oversight.
Infrastructure Context
Does the provider evaluate the existing environment before recommending changes?
Relevant considerations include personnel, systems, workflows, approval authority, internal controls, reporting needs, funding restrictions, contractual obligations, and operational dependencies.
Recommendations should explain why a change is necessary, which requirement it addresses, and what can appropriately remain in place.
Additional technology, staffing, or outsourcing should not be presumed to improve performance without considering the environment in which it will operate.
Accountability
Establish clear responsibility for financial execution, review, reporting, escalation, and executive oversight.Accountability should be reflected in the engagement agreement and operating arrangements—not left to informal assumptions.
Continuity
Determine how financial responsibilities will be maintained during absences, personnel transitions, organizational changes, and evolving requirements.Consider documentation, coverage arrangements, access to information, and the transfer of institutional knowledge.
Communication
Define expectations for leadership access, reporting schedules, financial reviews, and issue resolution.Communication arrangements should support both routine coordination and matters requiring financial judgment or executive action.
Professional Boundaries
Distinguish financial management responsibilities from independent assurance, specialized tax matters, and other services requiring separate expertise or authorization.The engagement should identify when external professionals are required and how responsibilities will be coordinated without compromising professional independence.
Commercial Transparency
Document scope, pricing, exclusions, client responsibilities, termination provisions, and circumstances requiring engagement adjustments.Leadership should understand what the provider is assuming, what remains outside the engagement, and how changes will be evaluated and approved.
Determining Organizational Fit
The most suitable provider is not necessarily the firm advertising the greatest number of services.It is the provider whose capabilities, accountability arrangements, operating model, and engagement structure correspond to organizational requirements.
Specialized accounting, controller, and CFO providers may be appropriate where complementary internal capabilities already exist. Integrated financial management may be more appropriate where the organization requires unified execution and continuing executive oversight.
An effective selection process should answer a central question:
Who will execute, review, coordinate, and sustain each required financial responsibility—and through what operating environment?
Financial Infrastructure Alignment and Applied Methodology
Effective financial management requires alignment between organizational responsibilities and the systems, workflows, controls, information, and oversight arrangements through which those responsibilities are fulfilled.
Where alignment is insufficient, organizations may experience reporting delays, fragmented execution, unclear accountability, and operational dependency despite investments in personnel or technology.
Reporting, governance, and operations must therefore be evaluated as interdependent functions of one financial environment.
Operational activity generates financial information. Reporting transforms that activity into information for management and executive decisions. Governance establishes the authority, controls, and accountability governing those responsibilities.
The effectiveness of each function depends on its relationship with the others.
An Applied Framework: Integrated Financial Infrastructure™
Drawing on more than 15 years of executive financial management experience, Syndia Alexandre developed Integrated Financial Infrastructure™ to address the recurring gap between evolving organizational requirements and the financial infrastructure supporting them.
The methodology connects financial management responsibilities, organizational accountability, and operational continuity through an integrated framework for evaluating, establishing, and sustaining the financial environment organizations require.
Kontab Advisory applies this methodology through three formal engagement stages:
Financial Infrastructure Diagnostic — Evaluate
Evaluates the existing financial environment against organizational requirements, identifies gaps and dependencies, and establishes evidence-based engagement recommendations.Financial Infrastructure Alignment — Establish
Establishes the required financial environment by aligning financial responsibilities, accounting and treasury activities, systems, workflows, internal controls, and reporting arrangements.Financial Infrastructure Oversight — Sustain
Maintains alignment through ongoing strategic executive financial management, coordinated financial operations, and executive oversight as organizational requirements evolve.
The methodology connects the performance of financial responsibilities with the infrastructure necessary to sustain them.
The objective is not simply to add capacity or replace technology. It is to establish and manage the financial environment the organization requires.
For additional information, explore Kontab Advisory's Capabilities and Integrated Financial Infrastructure™ Methodology.
Conclusion
Financial management, financial infrastructure, and provider evaluation address distinct but connected questions.
Financial management identifies the responsibilities that must be executed and overseen.
Financial infrastructure establishes the environment required to perform and sustain those responsibilities reliably.
Provider evaluation determines whether professional capabilities, operating arrangements, and engagement commitments correspond to organizational requirements.
The central executive question is not simply which services a provider offers.
It is whether the organization's financial responsibilities, infrastructure, and oversight are sufficiently aligned to support reliable information, accountable governance, and operational continuity.
Infrastructure maturity precedes scalability.
Scaling Pains: The Misdiagnosis of Infrastructure Strains
Recognizing the structural conditions behind financial management challenges during organizational change.
-
Scaling Pains: The Misdiagnosis of Infrastructure Strains
Financial Infrastructure Intelligence Series · By Syndia Alexandre, Founder & CEO
Why organizations misdiagnose infrastructure strain as a staffing, technology, or capacity problem—and why diagnosis must precede intervention.
When Growth Outpaces Infrastructure
Organizational growth rarely begins with dysfunction. It begins with success.
A new program launches. Another location opens. Additional funding is secured. Reporting obligations expand. A new legal entity is established. Individually, these developments may be manageable. Collectively, they change the requirements placed on an organization's financial environment.
Existing processes often continue to function during this transition. Teams adapt, spreadsheets expand, manual workarounds become routine, and experienced employees compensate for changing requirements through institutional knowledge and additional effort.
Leadership may interpret this adaptability as operational resilience. Yet the organization may be relying on financial infrastructure that was never established to support its evolving requirements.
The resulting strain is not necessarily a failure of personnel, technology, or organizational capacity. It may indicate a structural deficit between what the organization now requires and what its financial infrastructure can reliably support.
Most organizations do not recognize this distinction until operational strain becomes visible—or an attempted solution fails to produce lasting improvement.
Recognizing Infrastructure Strain
Infrastructure strain develops as organizational requirements exceed the capacity of existing financial systems, workflows, controls, and accountability structures.
Its effects become visible across three interconnected functions: reporting, governance, and operations.
Reporting: Information Asymmetry
Delayed reporting and unreliable financial information.
Financial close periods extend. Reconciliations require increasing manual intervention. Financial information becomes available after critical decisions must be made, limiting leadership's ability to evaluate performance, allocate resources, and respond to emerging conditions.
The problem extends beyond reporting speed. It concerns whether financial information remains sufficiently reliable, timely, and connected to organizational activity to support executive decision-making.
Governance: Unclear Accountability
Undefined responsibilities and inconsistent financial oversight.
Approval workflows become inconsistent. Financial authority is insufficiently defined. Internal controls depend on individual judgment rather than established procedures, while audit preparation becomes an episodic effort to reconstruct documentation and reconcile outstanding matters.
As organizational requirements evolve, unclear accountability weakens the relationship between financial information, management responsibility, and executive oversight.
Operations: Personnel Dependency
Concentrated expertise and fragmented financial operations.
Critical workflows become dependent on a limited number of employees. Accounting, treasury, and operational information remain distributed across disconnected systems, spreadsheets, and undocumented processes.
Routine activities require repeated coordination and manual intervention. Personnel transitions, absences, and expanding transaction volumes expose operational dependencies that were previously absorbed through individual effort.
These conditions are interconnected. Fragmented operations compromise reporting reliability, unreliable information constrains oversight, and unclear accountability allows operational weaknesses to persist.
The visible symptoms differ, but the underlying condition may be the same: organizational requirements have outpaced the financial infrastructure supporting them.
The Three Predictable Responses
When these conditions emerge, leadership frequently responds through additional staffing, new technology, or increased effort.
Each intervention can be appropriate. None should be assumed to resolve the underlying structural condition without first establishing what the organization requires.
1. Hire Additional Personnel
Infrastructure strain is often interpreted as insufficient staffing capacity.
An additional accountant, controller, or financial administrator may increase processing capacity and distribute workloads. However, adding personnel to fragmented workflows, undocumented procedures, and disconnected reporting structures does not independently establish a reliable financial environment.
Additional staffing may become necessary, but its effectiveness depends on whether responsibilities, processes, systems, and controls are appropriately defined.
Without that alignment, organizations risk increasing personnel costs while preserving the conditions responsible for the original strain.
2. Implement New Technology
When additional staffing does not resolve the problem, attention frequently shifts to accounting software, reporting platforms, dashboards, and automation.
Technology can improve processing efficiency, reporting accessibility, and workflow execution. Its effectiveness, however, depends on the structure of the financial environment in which it operates.
Software does not independently determine organizational responsibilities, establish appropriate approval authority, define reporting requirements, or resolve conflicting workflows.
Implementing new technology without addressing these conditions can reproduce existing fragmentation within a different system.
The organization may process information faster without improving the reliability, accountability, or coordination of the underlying financial activities.
3. Increase Operational Effort
When additional resources are constrained, organizations often rely on existing personnel to absorb the strain.
Employees work longer hours, perform additional reconciliations, maintain parallel spreadsheets, and develop manual procedures to compensate for infrastructure limitations.
These responses may sustain operations temporarily. Over time, however, temporary workarounds become embedded operating practices, increasing personnel dependency and reducing organizational continuity.
The organization becomes increasingly reliant on the individuals who understand how disconnected processes fit together.
The problem is not necessarily the intervention. It is the sequence in which the intervention is selected.
Staffing, technology, and additional effort address particular operational needs. They do not establish whether the organization's existing financial infrastructure is aligned with its requirements.
The Cost of Misdiagnosis
When leadership responds to infrastructure strain without identifying its underlying condition, organizations risk investing in solutions that address symptoms while preserving structural deficiencies.
Additional personnel may increase capacity without improving coordination. New systems may accelerate fragmented processes. Manual workarounds may sustain short-term execution while increasing operational dependencies.
The consequences extend beyond administrative inefficiency.
Delayed reporting constrains executive visibility. Unclear accountability weakens financial oversight. Fragmented operations complicate resource allocation, increase coordination demands, and expose continuity risks.
As these conditions persist, leadership becomes increasingly occupied with resolving recurring operational problems rather than directing financial resources toward organizational priorities.
The financial environment continues to function, but its reliability becomes increasingly dependent on intervention.
This distinction matters: an organization can expand its operating capacity without strengthening the infrastructure required to sustain that capacity.
Diagnosis Before Intervention
Addressing infrastructure strain begins by establishing the organization's requirements and evaluating the financial environment against them.
This evaluation must extend beyond staffing levels, software capabilities, and transaction volumes.
It must determine whether reporting, governance, and operations are appropriately aligned with the organization's funding structures, contractual obligations, operating activities, accountability requirements, and executive decision-making needs.
A structured diagnostic establishes the basis for determining:
Which financial responsibilities, processes, systems, and controls are required.
Where existing infrastructure is insufficient, fragmented, or unnecessarily dependent on individuals.
Whether additional personnel, technology, process redesign, or structural alignment is warranted.
How required improvements should be prioritized and sustained as organizational requirements evolve.
The purpose is not to presume that every organization needs additional infrastructure or a complete operational transformation. It is to establish what the organization requires, what already functions reliably, and where intervention is justified.
Through Integrated Financial Infrastructure™, Kontab Advisory applies this approach to evaluate, align, and sustain organizational financial management across reporting, governance, and operations.
Infrastructure Maturity Precedes Scalability
Growth increases organizational requirements. Infrastructure maturity determines how reliably the financial environment can support them.
Sustainable scalability requires more than additional resources or faster processing. It depends on reliable financial information, defined accountability, coordinated operations, and the capacity to maintain these conditions as requirements evolve.
Organizations that distinguish structural deficiencies from isolated capacity constraints can make more informed decisions about staffing, technology, financial management, and operational change.
Diagnosis establishes what must change. Alignment establishes the required financial environment. Ongoing oversight sustains that alignment.
Infrastructure maturity precedes scalability.
Infrastructure Strains: The Erosion of Scalability
Examining how fragmented financial environments constrain organizational capacity.
-
Infrastructure Strains: The Erosion of Scalability
Financial Infrastructure Intelligence Series · By Syndia Alexandre, Founder & CEO
How unresolved infrastructure strain becomes embedded in organizational operations, progressively constrains scalability, and increases the demands of structural correction.
When Infrastructure Strain Becomes Institutionalized
Infrastructure strain rarely prevents organizational growth immediately. More often, organizations continue expanding while relying on financial processes, systems, and accountability structures that have not evolved alongside their requirements.
A fragmented reporting process within a twenty-person organization may remain manageable through individual effort. An experienced employee maintains the necessary spreadsheets, resolves exceptions, and compensates for gaps in established workflows.
As the organization expands to eighty employees, additional programs, funding sources, and operating locations introduce new financial responsibilities. Existing workarounds are extended to accommodate them. New personnel inherit established practices, reporting requirements multiply, and manual coordination becomes increasingly necessary.
The underlying structural condition may remain unchanged, but its consequences expand with the organization.
Over time, processes originally intended to compensate for temporary limitations become embedded operating practices. What once required occasional intervention becomes a recurring administrative obligation.
Infrastructure strain becomes difficult to recognize when the organization has adapted its operations around it.
The resulting erosion is gradual. Financial infrastructure continues to function, but each additional organizational requirement demands increasing coordination, intervention, and institutional knowledge.
The Three Stages of Infrastructure Erosion
Unresolved infrastructure strain can progress through three organizational conditions: absorption, adaptation, and exposure.
These stages describe how structural deficiencies become increasingly embedded and visible. They are an analytical framework, not a fixed timeline or an inevitable progression for every organization.
Stage One: Absorption
Personnel compensate for infrastructure limitations.
At this stage, financial processes continue functioning because individuals absorb the additional effort required to maintain them.
A finance manager extends the monthly close to complete reconciliations. A program director develops a separate spreadsheet to obtain information unavailable through established reporting. An experienced employee identifies errors through institutional knowledge rather than documented controls.
The organization may experience longer processing times or increasing workloads without recognizing a broader structural condition.
Existing personnel provide the flexibility that financial infrastructure lacks.
The strain remains largely invisible because individuals compensate before its consequences reach leadership.
Stage Two: Adaptation
Temporary workarounds become established operating practices.
As organizational requirements continue evolving, compensating activities become routine.
Manual reconciliations are incorporated into the monthly close. Parallel spreadsheets become recurring reporting tools. Undocumented procedures are passed between employees, and responsibility for critical processes concentrates around those with the greatest institutional knowledge.
New personnel learn to operate within these arrangements rather than question whether the underlying processes remain appropriate.
Over time, the distinction between an established financial process and a workaround becomes increasingly difficult to identify.
The organization has adapted to its infrastructure limitations without necessarily addressing them.
What began as an exception becomes part of the operating environment.
Stage Three: Exposure
Infrastructure limitations become visible through organizational demands or disruption.
Exposure occurs when existing workarounds can no longer absorb changing requirements or an event reveals their underlying dependencies.
A key employee leaves. An auditor requests documentation. A funder requires additional reporting. A board member needs timely financial information. A new program or operating location increases the demands placed on established processes.
The organization must now address deficiencies that may have accumulated across reporting, governance, and operations.
Correction becomes more involved because the original structural condition is no longer isolated. It has influenced workflows, responsibilities, reporting practices, and institutional expectations.
Leadership may need to restore reporting reliability, clarify accountability, document institutional knowledge, redesign processes, and maintain operational continuity simultaneously.
The organization is no longer correcting an isolated process. It is addressing the accumulated consequences of operating around that process.
How Infrastructure Strain Erodes Scalability
The erosion of scalability is not limited to increasing administrative workloads. It affects an organization's ability to absorb new requirements while maintaining reliable information, accountable oversight, and coordinated operations.
Three consequences become particularly significant.
1. The Capacity Cost of Manual Integration
Fragmented financial systems and workflows require personnel to connect activities that should operate through established processes.
Reconciliations, duplicate data entry, spreadsheet consolidation, and repeated coordination consume time that could otherwise support financial analysis, planning, and organizational priorities.
As transaction volumes, programs, and funding requirements expand, these activities can increase faster than the organization's ability to manage them efficiently.
Additional personnel may temporarily absorb the workload, but without structural alignment, the organization continues allocating resources to compensate for fragmentation.
The resulting capacity constraint is not simply a shortage of employees. It reflects the increasing effort required to sustain disconnected financial operations.
2. Information Asymmetry and Decision Lag
Organizational expansion increases the importance of reliable information concerning cash flow, financial obligations, program performance, and resource allocation.
When information remains distributed across disconnected systems and manually maintained records, producing a consolidated financial picture requires additional reconciliation and validation.
Leadership may receive financial information after the period in which it would have been most useful.
Delayed reporting limits the organization's ability to evaluate emerging requirements, identify financial exposure, assess capacity, and make timely resource decisions.
The organization may possess substantial financial data without having dependable information available when executive decisions are required.
3. Increasing Governance and Continuity Exposure
Scalability requires financial responsibilities, controls, and approval structures that remain effective as organizational activities expand.
When these arrangements depend on informal practices or individual judgment, new programs, personnel, funding sources, and operating locations increase the demands placed on existing governance structures.
Inconsistent controls can complicate compliance, weaken audit readiness, and obscure financial accountability.
Concentrated institutional knowledge also creates continuity risks. Personnel transitions may interrupt essential processes or require significant effort to reconstruct undocumented responsibilities and workflows.
As requirements increase, governance and operational weaknesses that were previously manageable can become more consequential.
Together, these conditions reduce the organization's ability to accommodate additional complexity without disproportionate increases in effort, coordination, and risk.
Why the Timing of Intervention Matters
The significance of infrastructure strain is determined not only by the severity of the original deficiency but also by how extensively that deficiency has become embedded in organizational operations.
During absorption, correction may involve documenting responsibilities, strengthening controls, or adjusting specific workflows before compensating practices become widespread.
During adaptation, intervention may require replacing established workarounds, integrating fragmented systems, clarifying responsibilities, and changing operating practices across multiple functions.
During exposure, organizations may face these same requirements while responding to immediate reporting demands, personnel transitions, audit requests, or stakeholder concerns.
The underlying deficiency may be similar at each stage. The conditions surrounding its correction are not.
As infrastructure limitations become embedded, remediation can require broader organizational coordination, additional resources, and more extensive change management.
This does not mean early intervention is always simple or that delayed correction is necessarily unsuccessful.
It means the timing of intervention influences the scope, complexity, and operational demands of restoring infrastructure alignment.
Organizations that recognize structural strain before it becomes institutionalized have greater opportunity to evaluate and address deficiencies without simultaneously managing the consequences of prolonged dependency.
From Infrastructure Strain to Structural Alignment
Addressing accumulated infrastructure strain requires more than increasing processing capacity or replacing individual systems.
Leadership must first establish the financial environment required by the organization's current and evolving responsibilities.
That determination requires examining reporting, governance, and operations as interconnected functions.
Reporting must produce reliable financial information that supports executive decision-making.
Governance must establish defined responsibilities, appropriate controls, and accountable oversight.
Operations must support coordinated financial activity, resource visibility, documented workflows, and organizational continuity.
The required intervention depends on the organization's actual conditions. Some environments may need targeted process improvements. Others may require broader structural alignment involving systems, responsibilities, controls, and financial management practices.
Through Integrated Financial Infrastructure™, Kontab Advisory evaluates organizational requirements and existing infrastructure conditions to determine the alignment necessary to support ongoing strategic executive financial management.
The diagnostic process establishes the basis for identifying structural deficiencies, evaluating their operational consequences, and prioritizing appropriate intervention.
The objective is not to eliminate every operational constraint. It is to establish financial infrastructure that remains aligned with organizational requirements as those requirements evolve.
Infrastructure Maturity Preserves Organizational Capacity
Infrastructure strain rarely erodes scalability through a single event.
It develops as compensating effort becomes routine, workarounds become institutionalized, and structural limitations increasingly influence the organization's ability to operate.
Growth may continue throughout this progression. The consequences become visible when additional requirements demand more coordination, reporting reliability, governance discipline, or operational capacity than the existing environment can consistently support.
Recognizing infrastructure strain before exposure provides leadership with an opportunity to address structural deficiencies while maintaining greater control over the timing and scope of intervention.
Absorption conceals strain. Adaptation embeds it. Exposure reveals its accumulated consequences.
Infrastructure maturity is the discipline of identifying and addressing these conditions before they constrain organizational continuity and sustainable scalability.
Infrastructure maturity precedes scalability.
Infrastructure Alignment: The Anatomy of Infrastructure Maturity
Understanding the relationship between reporting, governance, and operational execution.
-
Infrastructure Alignment: The Anatomy of Infrastructure Maturity
Financial Infrastructure Intelligence Series · By Syndia Alexandre, Founder & CEO
How reporting, governance, and operations become a coordinated financial environment—and why structural alignment, rather than isolated improvements, establishes the foundation for infrastructure maturity.
From Infrastructure Strain to Structural Alignment
The first two publications in this series examined how infrastructure strain develops and becomes embedded in organizational operations.
Organizations initially misdiagnose structural deficiencies as staffing, technology, or capacity problems. When those deficiencies remain unresolved, compensating practices become institutionalized, increasing operational demands and progressively constraining scalability.
The next question is what changes when an organization moves beyond infrastructure strain.
The answer is structural alignment.
Organizations frequently begin by addressing their most visible financial management problem. Reporting takes too long, so the close process is redesigned. A key employee prepares to leave, so additional personnel are recruited. Leadership needs better information, so a reporting platform is introduced.
Each intervention may be appropriate. Yet improving an individual function does not necessarily change the broader financial environment.
Reporting can become faster while governance remains inconsistent. Additional personnel can increase capacity while operational dependencies remain undocumented. New technology can improve processing without establishing the responsibilities and controls required to sustain reliable execution.
The organization may resolve an immediate problem without addressing the structural conditions that continue producing others.
Infrastructure alignment changes the relationship between financial functions rather than treating each deficiency as an isolated problem.
The Three Functions of Structural Alignment
Infrastructure maturity is not determined by the number of financial systems an organization uses or the size of its accounting team.
It depends on whether reporting, governance, and operations function together in accordance with organizational requirements.
These functions perform distinct responsibilities but operate within one interconnected financial environment.
Reporting: Reliable Information for Decision-Making
Reporting transforms financial activity into information leadership can use to evaluate organizational performance, financial obligations, resource allocation, and emerging requirements.
A structurally aligned reporting environment establishes appropriate accounting processes, reconciliations, close procedures, financial statements, management reporting, and reporting responsibilities.
Financial information is produced through defined processes rather than repeatedly reconstructed from disconnected records.
The objective is not simply faster reporting. It is reliable information available within the timeframe required for effective decision-making.
Alignment outcome: Decision Intelligence
Governance: Defined Accountability and Disciplined Oversight
Governance establishes how financial responsibilities are assigned, transactions are authorized, information is reviewed, and organizational obligations are monitored.
A structurally aligned governance environment connects financial authority, internal controls, approval procedures, compliance requirements, and executive oversight to the activities they govern.
Accountability becomes embedded in established responsibilities and operating procedures rather than depending primarily on individual judgment or retrospective intervention.
Audit readiness is supported through consistent documentation, control execution, and financial management practices.
Alignment outcome: Accountable Oversight
Operations: Coordinated Execution and Resource Visibility
Operations encompass the financial activities and workflows through which organizational resources are managed.
These include transaction processing, accounts payable and receivable, payroll, treasury management, cash management, financial systems, and related administrative processes.
A structurally aligned operational environment establishes documented workflows, appropriate system integration, clear responsibilities, and continuity procedures.
Routine execution becomes less dependent on individual memory, while leadership gains greater visibility into the financial activities and resources supporting organizational operations.
Alignment outcome: Resource Transparency
These three functions are interdependent.
Operational activity produces the financial information required for reporting. Governance establishes the controls and accountability governing that activity and its resulting information. Reporting enables leadership to evaluate performance, obligations, and the effectiveness of financial management.
Weakness in one function can compromise the reliability of the others.
Structural alignment establishes the conditions through which these responsibilities operate as one coordinated financial environment.
How Structural Alignment Works
Alignment requires more than connecting software platforms or automating individual transactions.
It begins by establishing the financial responsibilities, information requirements, control expectations, and operating processes appropriate to the organization.
Those requirements determine how activities should move through the financial environment, where accountability must be established, and how information should become available for oversight.
Three mechanisms are particularly important.
1. Coordinated Financial Workflows
Financial activities should follow defined processes connecting transaction initiation, authorization, execution, recording, reconciliation, and reporting.
Responsibilities and system interactions must be established so that information moves between functions without unnecessary duplication or repeated reconstruction.
Automation may support these processes where appropriate, but the required workflow must first be understood and defined.
2. Embedded Accountability and Controls
Controls should operate at the points where financial decisions and transactions occur.
Approval authority, documentation requirements, funding restrictions, budget verification, and compliance responsibilities should be incorporated into relevant workflows.
This reduces reliance on retrospective corrections and supports consistent application of organizational policies.
3. Reliable Information Continuity
Financial information should remain traceable from the underlying activity through accounting records, reconciliations, and management reporting.
Appropriate integration, validation, and review procedures support the reliability of that information.
The objective is to reduce information asymmetry by establishing dependable relationships between operational activity, financial records, and executive reporting.
Together, these mechanisms connect financial execution with accountability and decision-making.
Structural Alignment in Practice: A Transaction Example
Consider a vendor invoice entering an organization's financial environment.
In a fragmented environment, invoice processing may involve separate email approvals, manually maintained budget records, repeated data entry, disconnected payment systems, and subsequent reconciliation before the transaction appears reliably in financial reporting.
In an aligned environment, the same activity follows a defined sequence connecting operations, governance, and reporting.
The following five steps illustrate a possible transaction workflow. They are not a universal software configuration or additional stages of the Integrated Financial Infrastructure™ engagement methodology.
Step 1. Operations: Transaction Initiation
A vendor invoice is received through an established submission process.
Required information is captured, validated for completeness, and associated with the appropriate vendor, organizational activity, and supporting documentation.
The transaction is prepared for review according to established procedures.
Control condition: Required transaction information is complete and available for verification.
Step 2. Governance: Verification and Budget Review
The transaction is evaluated against applicable requirements, which may include contract terms, purchase authorization, available budgets, funding restrictions, and organizational policies.
Exceptions are identified for appropriate review before processing continues.
Control condition: Applicable financial and contractual requirements have been evaluated.
Step 3. Governance: Authorization
The transaction is routed to the individual or role with designated approval authority.
Authorization follows established responsibilities, approval thresholds, and documentation requirements.
The decision is recorded to support accountability and subsequent review.
Control condition: Required authorization is documented.
Step 4. Operations: Transaction Execution and Recording
Following authorization, the transaction proceeds through the appropriate accounting and payment workflows.
Financial records are updated according to applicable accounting procedures, with supporting documentation retained and reconciliations performed as required.
Control condition: The transaction is appropriately recorded and supported.
Step 5. Reporting: Financial Information and Executive Visibility
Recorded financial activity becomes available for relevant financial statements, budget monitoring, cash-flow analysis, and management reporting.
Validation and reconciliation procedures support the reliability of information presented to leadership.
Reporting frequency and accessibility are determined by organizational requirements and system capabilities.
Control condition: Financial information is available for appropriate reporting and oversight.
What the Example Demonstrates
The significance of this workflow is not that every step must be automated or completed instantaneously.
It is that financial activity, accountability, and information remain connected throughout the transaction lifecycle.
Operations execute the activity. Governance establishes the requirements and authority under which it proceeds. Reporting makes the resulting financial information available for management and oversight.
The same principles apply across payroll, treasury management, restricted funding, financial close, and other financial responsibilities.
Infrastructure alignment establishes the relationship between execution, accountability, and information—not merely the technology through which transactions pass.
What Changes as Alignment Takes Hold
Organizations may experience the effects of alignment before those improvements become visible in formal performance measures.
Leadership receives more consistent explanations of financial results. Employees rely less on undocumented institutional knowledge. Recurring financial questions can be answered through established records and processes rather than reconstructed information.
Over time, these changes can support measurable operational improvements.
Reporting Becomes Dependable
Defined processes, consistent reconciliations, and established reporting responsibilities can reduce delays and improve information reliability.
Financial close periods become more predictable, and leadership gains greater confidence in the information supporting decisions.
Governance Becomes Consistent
Responsibilities, approvals, and controls are applied through established procedures.
Financial oversight becomes less dependent on episodic intervention, while documentation and review practices support continuing audit readiness.
Operations Become Repeatable
Documented workflows and coordinated systems reduce unnecessary manual intervention and dependence on individual institutional knowledge.
Personnel transitions become more manageable, and financial activities can accommodate changing requirements with greater consistency.
These improvements do not occur automatically or uniformly. Their extent depends on existing conditions, organizational requirements, implementation decisions, and sustained management discipline.
Infrastructure maturity develops as these conditions become established and maintained throughout the financial environment.
Diagnosis Determines What Alignment Requires
Diagnosis and alignment serve different purposes.
Diagnosis establishes the existing condition and determines what infrastructure is required.
Alignment establishes the financial environment identified through diagnostic findings.
A diagnostic evaluation examines organizational requirements alongside existing financial systems, workflows, controls, reporting practices, responsibilities, and operational dependencies.
Its findings determine whether the organization requires targeted improvements, broader integration, additional financial management capacity, or more extensive structural change.
Alignment then translates those findings into established responsibilities, coordinated processes, appropriate systems, controls, and reporting structures.
The objective is not to replace every existing process or system. It is to preserve what functions reliably, correct identified deficiencies, and establish the financial infrastructure required by the organization.
Through Integrated Financial Infrastructure™, Kontab Advisory applies this approach to strategic executive financial management across reporting, governance, and operations.
Alignment establishes the required operating conditions. Ongoing executive oversight sustains those conditions as organizational requirements evolve.
Infrastructure Maturity Is a Sustained Condition
Structural alignment does not mean an organization's financial environment becomes permanently fixed.
Organizations continue to expand, restructure, introduce programs, secure funding, change personnel, and encounter new reporting and accountability requirements.
These developments may require adjustments to existing processes, systems, responsibilities, and controls.
Infrastructure maturity depends on the organization's ability to maintain alignment as those requirements change.
Reporting must continue producing reliable information. Governance must maintain defined accountability. Operations must support coordinated execution and resource visibility.
The purpose of alignment is therefore not to establish an environment that never changes. It is to establish one capable of adapting without continually returning to fragmented processes and reactive intervention.
Diagnosis determines what the organization requires. Alignment establishes the required financial environment. Oversight sustains its effectiveness.
Infrastructure maturity precedes scalability.
Infrastructure Maturity: The Foundation for Effective Stewardship
Examining why infrastructure maturity matters as organizational requirements evolve.
-
Infrastructure Maturity: The Foundation for Effective Stewardship
Financial Infrastructure Intelligence Series · By Syndia Alexandre, Founder & CEO
Why infrastructure maturity is not a milestone achieved once—and how disciplined oversight sustains reporting reliability, governance accountability, and operational continuity as organizational requirements evolve.
Infrastructure Maturity Is Not a Permanent Condition
The first three publications in this series examined how infrastructure strain develops, why unresolved deficiencies progressively constrain scalability, and how structural alignment establishes coordinated financial management across reporting, governance, and operations.
The next question is what happens after alignment.
An organization may establish reliable reporting, defined accountability, and coordinated financial operations. Yet the requirements placed on that environment do not remain unchanged.
A new program launches. A department restructures. An experienced employee retires. Additional funding introduces reporting obligations. A board committee requests more detailed financial information.
Individually, these developments may require only limited adjustments. Collectively, they can change the conditions under which the organization's financial infrastructure must operate.
Without deliberate oversight, temporary workarounds may reappear. Documentation becomes outdated. Responsibilities shift without corresponding changes to established procedures. Reporting requires additional manual intervention, and controls no longer reflect the activities they were designed to govern.
The organization may continue operating without recognizing that its financial infrastructure is gradually becoming less aligned with its requirements.
Infrastructure maturity is not permanently secured through a successful alignment effort. It must be sustained as the organization evolves.
The Gradual Return of Infrastructure Strain
Organizations do not necessarily lose infrastructure maturity through a single operational failure.
More often, the early indicators are subtle.
A reconciliation takes longer than expected. A financial report requires additional adjustments. A recurring question can only be answered by a particular employee. An approval responsibility changes without corresponding documentation.
Individually, these developments may be manageable. Together, they can indicate that established financial processes, responsibilities, and controls are drifting away from organizational requirements.
This drift can occur across all three financial management functions.
Reporting: Declining Information Reliability
Reporting processes become increasingly dependent on manual adjustments, delayed reconciliations, or information maintained outside established systems.
Leadership may continue receiving financial statements, but the effort required to produce dependable information increases.
Governance: Weakening Accountability
Responsibilities, approval authorities, and control procedures no longer consistently reflect current organizational activities.
Oversight becomes increasingly dependent on retrospective review rather than established accountability throughout financial processes.
Operations: Renewed Personnel Dependency
Documented workflows become outdated, temporary exceptions become routine, and essential processes gradually concentrate around individuals with specialized institutional knowledge.
The organization begins recreating the conditions that previously contributed to infrastructure strain.
The earliest indication of declining maturity is often not an operational failure. It is the increasing effort required to maintain previously established reliability.
Why Stewardship Requires a Defined Cadence
Structural alignment establishes the required financial environment. Stewardship maintains its effectiveness as organizational requirements change.
This requires more than responding when a problem becomes visible.
A deliberate oversight cadence creates recurring opportunities to evaluate financial information, accountability, operational performance, and emerging requirements.
That cadence may include regular reconciliations, financial close procedures, management reporting, control reviews, documented responsibility assessments, and periodic evaluation of systems and workflows.
The frequency and depth of these activities should reflect the organization's requirements and operating environment.
The purpose is not to introduce additional review for its own sake. It is to identify changes before temporary exceptions become established structural deficiencies.
Reporting Oversight
Recurring review of financial information, reconciliation status, close performance, reporting requirements, and management information needs supports continuing reporting reliability.
Governance Oversight
Regular evaluation of responsibilities, approval authority, controls, compliance obligations, and financial decision processes supports accountable oversight.
Operational Oversight
Ongoing examination of transaction workflows, system performance, documentation, personnel dependencies, and resource coordination supports operational continuity.
These responsibilities must remain interconnected.
A change in operational activity may require revised controls. New funding obligations may require different reporting. Organizational restructuring may require changes to financial authority and process ownership.
Stewardship preserves alignment by maintaining the relationship between organizational requirements and the financial environment supporting them.
Financial Infrastructure Maturity: Four Organizational Conditions
Financial infrastructure maturity can be evaluated through four broad conditions: Fragmented, Developing, Aligned, and Strategic.
These conditions describe increasing reliability, accountability, coordination, and executive usefulness across reporting, governance, and operations.
They are not mandatory stages that every organization progresses through sequentially. An organization may demonstrate different levels of maturity across its financial functions, depending on its requirements and existing infrastructure.
Stage 1. Fragmented
Financial responsibilities operate through disconnected processes and individual intervention.
Reporting
Financial information requires extensive manual aggregation, reconciliation, or reconstruction. Reporting timelines and outputs may be inconsistent, limiting the reliability and availability of information for leadership.Governance
Financial responsibilities and approval procedures are insufficiently defined or inconsistently applied. Oversight is primarily reactive, and control execution may depend on individual judgment.Operations
Financial workflows are fragmented, documentation is limited, and essential activities depend heavily on institutional knowledge or disconnected systems.Organizational condition: Financial management remains dependent on compensating effort rather than consistently established infrastructure.
Stage 2. Developing
Core financial processes and responsibilities are becoming standardized.
Reporting
Recurring reporting procedures, established templates, and scheduled financial reviews improve consistency, although manual intervention may remain significant.Governance
Responsibilities, supervisory roles, approval procedures, and basic control expectations are increasingly documented and applied.Operations
Core workflows are documented, shared tools are introduced, and selected processes become more repeatable across personnel and departments.Organizational condition: Foundational financial management practices are established, but coordination across functions remains incomplete.
Stage 3. Aligned
Reporting, governance, and operations function through coordinated financial infrastructure.
Reporting
Established accounting processes, reconciliations, and reporting structures produce dependable information within required decision-making timelines.Governance
Defined responsibilities, embedded controls, documented approvals, and consistent review procedures support accountable financial oversight.Operations
Coordinated workflows, appropriate systems, established documentation, and continuity procedures reduce unnecessary manual intervention and personnel dependency.Organizational condition: Financial functions operate within a coordinated environment aligned with established organizational requirements.
Stage 4. Strategic
Financial infrastructure supports proactive organizational stewardship and evolving strategic requirements.
Reporting
Reliable financial information supports forecasting, scenario analysis, resource planning, and executive evaluation of organizational opportunities and obligations.Governance
Financial accountability and oversight are integrated into strategic planning, risk evaluation, resource allocation, and organizational decision-making.Operations
Coordinated financial processes and systems support changing organizational requirements, resource visibility, continuity, and sustainable expansion.Organizational condition: Established infrastructure enables leadership to evaluate future requirements and manage organizational resources proactively.
Interpreting Maturity
Higher maturity does not necessarily require more software, more automation, or more personnel.
A smaller organization with well-defined responsibilities, reliable reporting, appropriate controls, and documented processes may demonstrate stronger infrastructure maturity than a larger organization operating through sophisticated but disconnected systems.
The relevant standard is whether the financial environment reliably supports the organization's requirements.
The four conditions therefore provide a framework for evaluating infrastructure maturity—not a universal technology roadmap or a numerical guarantee of organizational readiness.
How Mature Infrastructure Supports Organizational Stewardship
Financial management encompasses the execution and oversight of financial responsibilities.
Organizational stewardship extends that responsibility toward the deliberate management, protection, and allocation of resources in support of current obligations and future requirements.
Effective stewardship depends on the quality of the financial environment through which leadership exercises judgment.
Three capabilities become particularly important.
1. Reliable Information for Resource Decisions
Leadership requires dependable financial information to evaluate cash flow, financial commitments, operating performance, and available resources.
Mature reporting infrastructure supports informed decisions by reducing uncertainty about the organization's financial condition.
It also strengthens the relationship between historical financial activity and forward-looking planning.
2. Accountable Governance and Financial Oversight
Stewardship requires defined authority, appropriate controls, and disciplined review of financial responsibilities.
Mature governance infrastructure establishes accountability throughout financial operations and supports leadership's ability to evaluate obligations, risks, and resource decisions.
It also maintains the documentation and oversight practices necessary to support audit readiness and changing compliance requirements.
3. Operational Continuity and Resource Transparency
Stewardship depends on the organization's ability to maintain financial responsibilities through personnel transitions, operational changes, and evolving requirements.
Mature operational infrastructure reduces unnecessary reliance on undocumented knowledge, strengthens coordination, and improves visibility into how organizational resources are managed.
Together, these capabilities support executive judgment, organizational continuity, and sustainable scalability.
Infrastructure maturity does not replace leadership judgment. It establishes the conditions through which that judgment can be exercised more reliably.
From Alignment to Ongoing Oversight
Diagnosis, alignment, and oversight address distinct organizational responsibilities.
Diagnosis evaluates. It establishes organizational requirements, examines existing financial conditions, and determines the infrastructure needed.
Alignment establishes. It implements the required financial responsibilities, workflows, systems, controls, and reporting structures identified through diagnostic findings.
Oversight sustains. It maintains infrastructure alignment through continuing financial management, accountability, review, and adaptation as organizational requirements evolve.
Alignment can be evaluated against defined implementation objectives. Oversight, however, is an ongoing responsibility because organizational requirements and operating conditions continue changing.
Through Integrated Financial Infrastructure™, Kontab Advisory integrates these responsibilities within its strategic executive financial management model.
Ongoing oversight supports reporting reliability, governance accountability, and operational continuity through established management practices and regular engagement with organizational leadership.
The objective is not to prevent every future deficiency. It is to recognize changing requirements, evaluate emerging conditions, and maintain appropriate alignment before recurring workarounds become embedded.
Stewardship Sustains Infrastructure Maturity
An organization does not demonstrate infrastructure maturity merely by completing an implementation, introducing new technology, or achieving a temporary improvement in reporting performance.
Maturity is demonstrated through the continued reliability of its financial environment as organizational requirements evolve.
Reporting remains dependable. Governance maintains defined accountability. Operations continue supporting coordinated execution and resource visibility.
When these conditions are sustained, leadership is better positioned to allocate resources, evaluate opportunities, fulfill obligations, and preserve organizational continuity.
Diagnosis establishes what is required. Alignment establishes the financial environment. Oversight sustains its effectiveness.
Infrastructure maturity precedes scalability.
Premature Automation: Why Systemic Speed Prior to Structural Maturity Escalates Institutional Risk
Examining how automation can amplify weaknesses in financial workflows when structural deficiencies remain unresolved.
-
Premature Automation: Why Systemic Speed Prior to Structural Maturity Escalates Institutional Risk
Related Financial Infrastructure Intelligence · By Syndia Alexandre, Founder & CEO
Why accelerating fragmented financial processes can compound errors, obscure accountability, and weaken oversight—and why structural readiness should determine automation decisions.
The Instinct Is Reasonable. The Sequencing Matters.
When financial operations begin to strain, automation is often among the first investments organizational leadership considers.
Manual reconciliations consume increasing time. Financial close periods extend. Reporting requires repeated intervention. Existing systems cannot consistently provide the information leadership needs.
A new accounting platform, automated workflow, reporting dashboard, or artificial intelligence application may appear to offer an immediate solution.
The rationale is understandable. Technology can improve processing efficiency, reduce repetitive activity, and increase access to financial information.
However, operational speed and infrastructure maturity are not interchangeable.
An organization may automate an inefficient process without correcting its underlying deficiencies. It may also accelerate a fragmented workflow without establishing the responsibilities, controls, and reporting structures necessary to govern it.
Automation can accelerate financial activity. It does not independently establish the conditions required for reliable financial management.
The relevant question is not simply whether a process can be automated. It is whether the process is sufficiently defined, controlled, and aligned with organizational requirements to support automation.
What Automation Actually Changes
Automation performs defined activities through configured rules, system integrations, algorithms, or other technology-enabled processes.
Depending on the application, it can reduce manual data entry, route transactions, apply validation rules, reconcile information, generate reports, and identify exceptions.
These capabilities can create meaningful operational improvements.
Their effectiveness, however, depends on the underlying process design, data quality, accountability arrangements, and control environment.
A workflow with unclear approval authority does not become appropriately governed simply because authorization requests are routed automatically.
A reconciliation process with unresolved data inconsistencies does not become reliable because information is aggregated more quickly.
A reporting system does not establish executive visibility merely by presenting financial information through a dashboard.
Automation executes or supports the logic embedded within its configuration.
If that logic reflects incomplete requirements, inconsistent processes, or unreliable information, automation may reproduce those deficiencies across a greater volume of activity.
Automation increases the capacity to execute a process. Infrastructure maturity determines whether that process is appropriate, reliable, and accountable.
The Illusion of Efficiency
Manual financial processes often contain visible friction.
Employees reconcile discrepancies, verify supporting documentation, review unusual transactions, and investigate inconsistent information.
These activities may be inefficient, but they can also reveal weaknesses in the underlying financial environment.
Automation can reduce that friction. Yet removing manual intervention without establishing appropriate controls may also remove opportunities to identify errors before they affect downstream activities.
An automated process may execute on schedule, produce consistent outputs, and appear operationally successful while repeatedly applying an incorrect rule or using unreliable information.
The appearance of efficiency can therefore obscure the quality of the underlying process.
A faster financial close is not necessarily a more reliable close. An automatically generated report is not necessarily decision-ready information. A completed workflow does not independently demonstrate that appropriate authorization occurred.
The distinction is between processing efficiency and financial management reliability.
Organizations require both, but one does not establish the other.
Four Structural Risks of Premature Automation
Automation introduced into a fragmented financial environment can amplify deficiencies across reporting, governance, and operations.
Four risks deserve particular attention.
1. Compounding Errors
Incorrect logic can be applied repeatedly across financial activity.
Manual errors may affect individual transactions or reporting periods. Automated errors can recur across every transaction processed under the same flawed configuration.
An incorrect account mapping, funding classification, approval rule, or reconciliation parameter may affect multiple transactions before the deficiency is identified.
As processing volume increases, correcting those errors can require extensive investigation, transaction adjustments, reconciliation, and documentation.
The risk is not that automation necessarily produces more errors. It is that an incorrectly configured process can reproduce the same error consistently and at scale.
Appropriate validation, exception monitoring, reconciliation, and change controls are therefore essential.
2. Obscured Accountability
Automated workflows can conceal unclear responsibilities.
When transactions move across multiple systems and integrations, responsibility for reviewing, authorizing, monitoring, and correcting activity must remain clearly established.
Without defined ownership, an organization may struggle to determine who approved a transaction, which system applied a rule, whether an exception was reviewed, or who is responsible for resolving a failure.
Technology can record activity without establishing accountability for that activity.
An effective automated process must preserve documented authority, appropriate segregation of duties, traceable decisions, and clear responsibility for exceptions.
Automation should support governance rather than substitute for it.
3. Concentrated Technical Dependency
Automation can replace one form of personnel dependency with another.
Organizations often automate manual processes to reduce reliance on employees who possess specialized institutional knowledge.
However, when automated workflows are poorly documented or maintained by a limited number of individuals, dependency may shift from the employee performing the process to the individual configuring or maintaining the technology.
Critical knowledge may become concentrated in integration settings, custom scripts, system rules, or undocumented technical decisions.
Personnel transitions, vendor changes, and system updates can then disrupt activities that appear independent of manual intervention.
Sustainable automation requires documented configurations, defined ownership, maintenance procedures, and appropriate continuity arrangements.
4. Unreliable Reporting and Audit Evidence
Automated output can appear authoritative without being sufficiently validated.
Financial dashboards, system-generated reports, and automated reconciliations may create confidence because information is produced consistently and presented in a standardized format.
That consistency does not independently establish accuracy or completeness.
If source information is unreliable, mapping rules are incorrect, or required controls are absent, automated reports may present misleading information to leadership.
Similarly, automated transaction processing does not guarantee that sufficient documentation, approval evidence, or audit trails exist.
Audit readiness depends on reliable records, appropriate controls, documented responsibilities, and evidence supporting financial activity.
Automation can strengthen these conditions when properly designed. Without them, it may complicate the verification of financial information.
The Conditions Automation Inherits
Automation operates within the financial environment established by the organization.
It inherits the systems, processes, responsibilities, information quality, and control arrangements already present.
Where these conditions are fragmented, automation may extend fragmentation into additional activities.
Where processes are undocumented, automation may make their underlying logic more difficult to understand.
Where accountability is unclear, automated decisions may become harder to attribute.
Where financial information is unreliable, faster processing may increase the volume of information requiring subsequent correction.
These consequences are not inevitable. They depend on implementation design, control effectiveness, system capabilities, and organizational oversight.
The principle remains:
Automation does not independently resolve structural deficiencies. Its effectiveness depends on the financial infrastructure supporting it.
Structural Readiness Before Automation
Before introducing automation, leadership should establish whether the relevant financial process is appropriately designed and governed.
This requires examining more than technical compatibility or anticipated processing savings.
Five questions provide a practical starting point.
1. Is the process defined?
Are the required activities, responsibilities, inputs, outputs, and exceptions documented and understood?
2. Is the information reliable?
Are source records, data definitions, account mappings, and reconciliation procedures sufficiently established?
3. Is accountability clear?
Are approval authorities, review responsibilities, segregation of duties, and exception ownership defined?
4. Are appropriate controls established?
Do validation, authorization, monitoring, documentation, and change-management procedures support the activity?
5. Can the process be sustained?
Are system ownership, maintenance responsibilities, technical documentation, continuity procedures, and oversight arrangements appropriate?
The answers determine whether automation is warranted, which activities should be automated, and what infrastructure improvements may be required first.
Not every process requires complete automation. Not every organization requires a new system.
The appropriate solution depends on verified organizational requirements.
The Order of Operations: Infrastructure Before Velocity
Structural alignment establishes the relationship between financial activity, accountability, and reporting.
It defines how transactions should move through the organization, where controls should operate, which responsibilities must be assigned, and how reliable information should become available for management and oversight.
Automation can then support those established processes.
For example, an appropriately designed accounts payable workflow may use technology to capture invoices, verify required information, route approvals, record transactions, and update financial records.
The value does not arise solely from completing those activities faster.
It arises from executing them through defined responsibilities, documented controls, reliable information, and coordinated systems.
Through Integrated Financial Infrastructure™, Kontab Advisory evaluates existing financial environments, establishes required infrastructure alignment, and sustains strategic executive financial management across reporting, governance, and operations.
Technology and automation are evaluated within that broader financial management context rather than treated as substitutes for it.
Infrastructure requirements determine process design. Process design establishes appropriate controls. Automation supports execution where justified.
Understanding the Automation Risk Trade-Off
Automation risk can be examined through the relationship between process maturity, execution volume, and control effectiveness.
Consider two illustrative environments.
Environment A: Fragmented Processes, High Automation
Financial workflows are inconsistently documented. Data sources require manual reconciliation. Approval responsibilities are unclear, and exceptions are not consistently monitored.
Introducing high-volume automation may increase processing capacity while also increasing the potential reach of configuration errors, unreliable information, and unresolved accountability.
Environment B: Defined Processes, Controlled Automation
Financial workflows are documented. Responsibilities and approval authorities are established. Information is validated, exceptions are monitored, and changes to automated processes are controlled.
Automation can improve efficiency while preserving appropriate review, traceability, and accountability.
The distinction is not automation speed alone.
It is the relationship between processing activity and the controls governing that activity.
Interpreting an Automation Risk Model
An illustrative risk model may compare process maturity and automation intensity to demonstrate how potential exposure changes under different assumptions.
However, numerical outputs from such a model should not be interpreted as verified probabilities, actual financial losses, or independently measured institutional risk unless supported by an established methodology and relevant evidence.
A model using maturity and speed scores can help leadership explore scenarios. It cannot, by itself, determine whether a particular organization is operationally prepared for automation.
Actual risk evaluation requires consideration of transaction volume, financial exposure, control design, system reliability, error detection, exception handling, and organizational requirements.
Automation readiness is established through evidence, not a speed or maturity score alone.
Infrastructure Maturity Determines the Value of Speed
Automation can strengthen financial management when it operates within a reliable, accountable, and coordinated environment.
It can reduce repetitive work, improve processing consistency, support timely reporting, and expand organizational capacity.
But these benefits depend on the structure of the processes being accelerated.
When automation precedes appropriate process design and controls, organizations risk increasing the speed and reach of existing deficiencies.
When automation follows structural evaluation and alignment, it can support more dependable execution and sustained operational improvement.
The executive question is therefore not simply:
How much faster can this process become?
It is:
What process are we accelerating, and is its underlying structure sufficiently reliable to support that speed?
Infrastructure maturity precedes scalability.