Financial Management, Infrastructure, and Provider Evaluation
Understand financial management responsibilities, the infrastructure required to support them, and how to evaluate providers against organizational requirements.
Financial Infrastructure Intelligence · By Syndia Alexandre, Founder & CEO
Financial Management, Infrastructure, and Provider Evaluation
Understand financial management responsibilities, the infrastructure required to support them, and how to evaluate providers against organizational requirements.
Financial Infrastructure Intelligence · By Syndia Alexandre, Founder & CEO
Financial management arrangements should be evaluated against the responsibilities an organization requires, not simply the services a provider advertises. This guide distinguishes financial responsibilities from their supporting infrastructure and provides a framework for evaluating professional capabilities, coordination, and accountability.
Financial Management Responsibilities
Financial management connects financial execution with the information, controls, planning, and leadership required to manage organizational resources.
Accounting establishes the financial record through transaction processing, reconciliations, financial close, and financial statement preparation. Controllership supports accounting quality, reporting integrity, documented policies, and internal controls. Financial planning connects historical performance with budgets, forecasts, cash expectations, and resource decisions. Executive financial leadership interprets these conditions in the context of organizational priorities.
These responsibilities are related but not interchangeable. Accurate accounting does not automatically establish effective planning. A forecast does not resolve incomplete records. Executive advice does not, by itself, ensure that transactions, reconciliations, and reporting are completed reliably.
Leadership should therefore identify both the responsibilities required and the arrangements connecting them. The relevant question is not simply whether financial work is being completed, but whether it is appropriately executed, reviewed, coordinated, and sustained.
Financial Infrastructure and Organizational Requirements
Financial infrastructure is the environment through which financial responsibilities operate. It includes systems, workflows, responsibilities, approval authority, controls, documentation, reporting structures, and oversight arrangements.
Infrastructure requirements depend on the organization's activities and obligations. Additional entities, programs, funding sources, locations, and contractual commitments may change how financial work must be performed and reviewed.
Revenue and employee count provide context, but they do not independently define complexity. A useful evaluation begins with questions such as:
What financial information does leadership require?
What obligations must the organization fulfill?
Which activities require authorization, documentation, or specialized review?
Where do processes depend on individuals?
Which existing arrangements function reliably?
The objective is not to introduce more infrastructure than necessary. It is to establish an environment appropriate to the responsibilities the organization must fulfill.
Accounting, Controller, CFO, and Integrated Service Models
Financial service labels describe general areas of emphasis. Actual responsibilities depend on the provider and engagement agreement.
Bookkeeping and outsourced accounting commonly address financial records, reconciliations, close procedures, and reporting. Controller services generally emphasize accounting supervision, reporting integrity, policies, and controls. CFO engagements may emphasize planning, forecasting, analysis, resource allocation, and executive decision support.
Some providers combine these responsibilities. Others concentrate on a narrower scope.
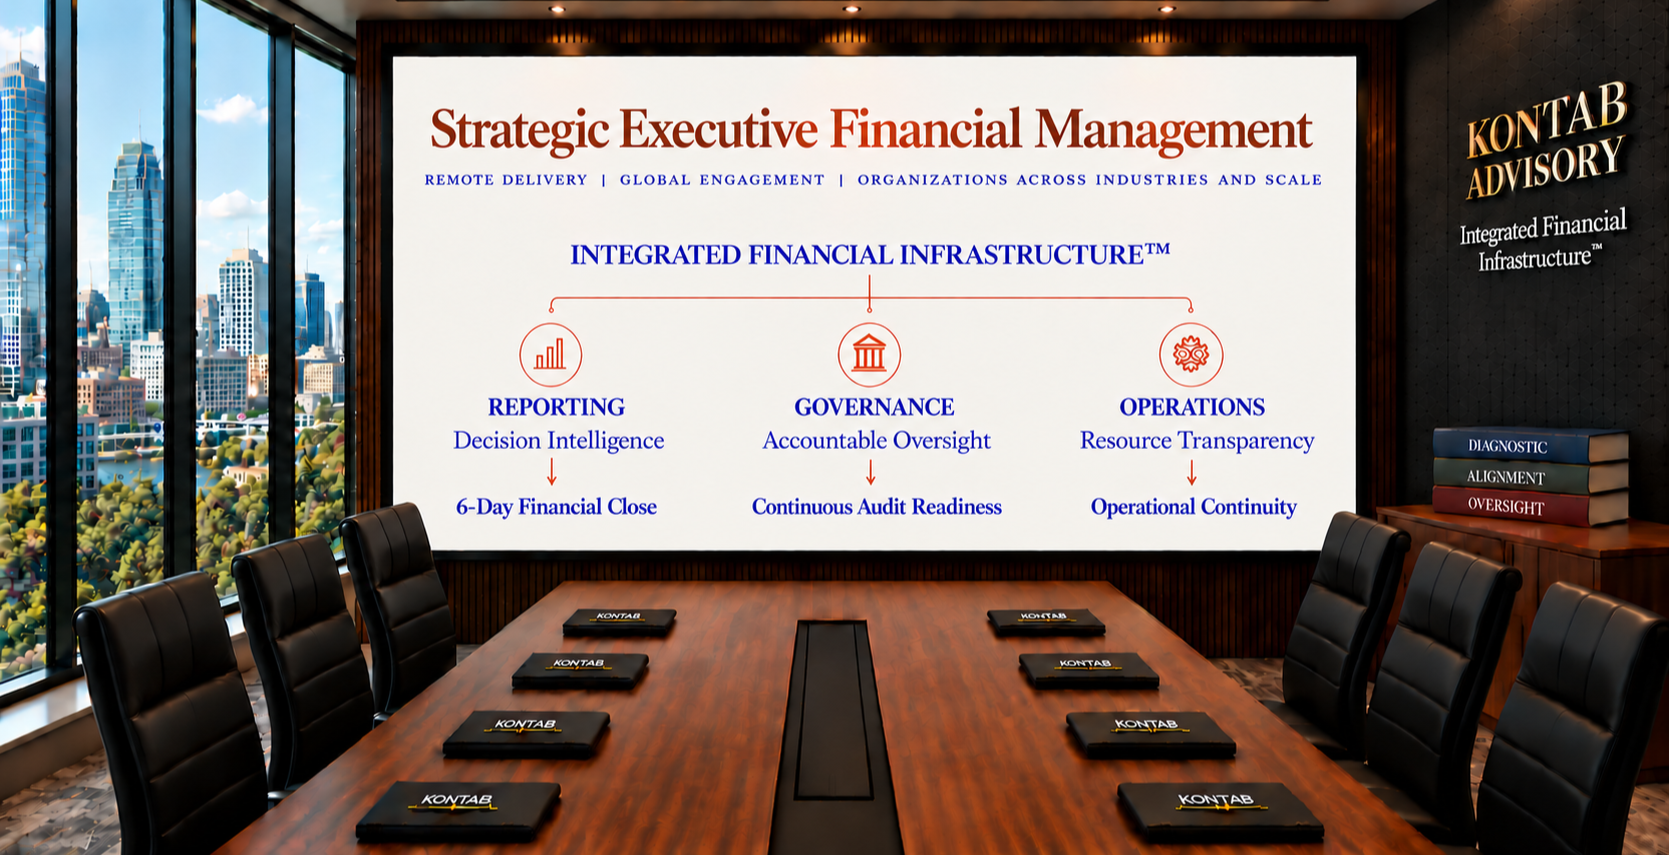
Integrated financial management connects execution, review, operations, and executive leadership within a coordinated arrangement. Its defining feature is not the number of advertised services, but how responsibilities work together.
Remote delivery describes how services are provided; it does not establish scope or availability. Likewise, a fractional title does not fully explain what a provider will perform. The same scrutiny applies to descriptions such as full-service or integrated: the engagement should identify what those terms mean in practice.
Evaluation should move beyond labels to documented responsibilities, deliverables, coordination procedures, and accountability.
Scope, Coordination, and Accountability
A financial management engagement should make three matters clear. These matters should be reflected in both the engagement agreement and operating procedures.
Scope: What will the provider perform, review, or coordinate? What remains with employees, leadership, or external specialists?
Coordination: How will information move through transaction processing, reconciliation, close, reporting, analysis, and decision-making? Who resolves missing information and exceptions?
Accountability: Who is responsible for execution, review, escalation, and corrective action when required work is incomplete, deadlines are missed, or controls do not operate as intended?
An arrangement can include capable professionals yet remain fragmented if handoffs are unclear. Similarly, a comprehensive service list can conceal responsibilities that no party has explicitly assumed.
A practical evaluation asks the provider to explain how a recurring financial process operates from beginning to end. For a monthly close, for example, identify who prepares reconciliations, reviews exceptions, approves adjustments, and communicates results to leadership.
Provider Fit, Engagement Terms, and Professional Boundaries
The appropriate provider is the one whose capabilities and commitments correspond to organizational requirements. A targeted accounting engagement may be sufficient where internal leadership manages planning, controls, treasury, and oversight. Broader support may be appropriate where responsibilities are fragmented or required capabilities are unavailable internally.
Before proceeding, clarify:
Scope and expected outputs.
Client responsibilities and information requirements.
Executive access and communication arrangements.
Pricing, exclusions, and adjustment provisions.
Continuity and transition arrangements.
Required specialized professionals.
Termination and information-transfer procedures.
Distinguish financial management from independent assurance and other specialized services. Preparing records and supporting an audit are different from issuing an independent audit opinion.
A suitable engagement does not assume every responsibility must move externally. It establishes who will fulfill each requirement and how the overall arrangement will remain accountable.
Effective provider selection begins with organizational requirements and concludes with clearly assigned responsibilities, coordinated execution, and accountable oversight.