Financial Infrastructure Strain, Alignment, and Scalability
Examine why reporting delays, recurring workarounds, and personnel dependencies emerge, and what leadership should evaluate before changing staff, systems, or processes.
Financial Infrastructure Intelligence · By Syndia Alexandre, Founder & CEO
Financial processes can become harder to sustain as organizational requirements change. This guide examines how infrastructure strain develops, why visible symptoms require investigation, and how structural alignment connects financial responsibilities with the environment needed to support them.
Recognizing Infrastructure Strain
Infrastructure strain becomes visible when established financial arrangements repeatedly struggle to support current organizational requirements. Indicators may include delayed close procedures, recurring reconciliation problems, inconsistent reports, unclear approvals, duplicated work, and dependence on individual employees.
No single indicator establishes a structural problem. An unusual reporting delay may reflect a temporary event. Repeated delays across several processes warrant a broader examination.
Leadership should consider both performance and the effort required to maintain it. Reports may arrive on schedule only because employees work excessive hours or reconstruct information outside established systems.
The question is not merely whether the financial environment continues operating. It is whether operations remain reliable, appropriately controlled, and sustainable under current conditions.
Distinguishing Symptoms from Underlying Causes
Similar symptoms can arise from different conditions. A delayed close may result from missing documents, insufficient capacity, unresolved reconciliations, unclear review responsibilities, or disconnected systems. Repeated reporting corrections may reflect classification errors, inconsistent definitions, or inadequate validation.
Selecting an intervention before establishing the cause can preserve the underlying weakness. Investigation should identify:
Where work stops or requires correction.
What information or authorization is missing.
Which responsibilities are unclear.
Whether the problem is recurring.
How existing systems and procedures contribute.
The appropriate intervention depends on the findings. Additional personnel may be necessary when capacity is insufficient. Technology changes may be warranted when existing tools cannot support verified requirements. Process redesign may be necessary when coordination is the constraint.
Several interventions may be required together. Their selection should follow findings rather than assumptions.
How Workarounds Become Operating Dependencies
A workaround can be a reasonable response to an immediate limitation. The concern arises when the organization relies on it without appropriate documentation, ownership, review, or continuity arrangements.
Kontab Advisory uses three descriptive conditions to examine these patterns:
Absorption: Individuals compensate for operational limitations through additional effort.
Adaptation: Compensating activities become recurring operating practices.
Exposure: A new demand or disruption reveals the dependency, such as an employee departure or a requirement to produce supporting information.
These conditions describe patterns of infrastructure strain, not mandatory stages through which every organization progresses. Leadership should distinguish controlled manual procedures from unmanaged dependencies. A documented spreadsheet with defined inputs and review may be appropriate. An unexplained spreadsheet that only one person can maintain presents a different issue.
The objective is not to eliminate every workaround. It is to determine which arrangements should be retained, formalized, redesigned, or replaced.
Connecting Reporting, Governance, and Operations
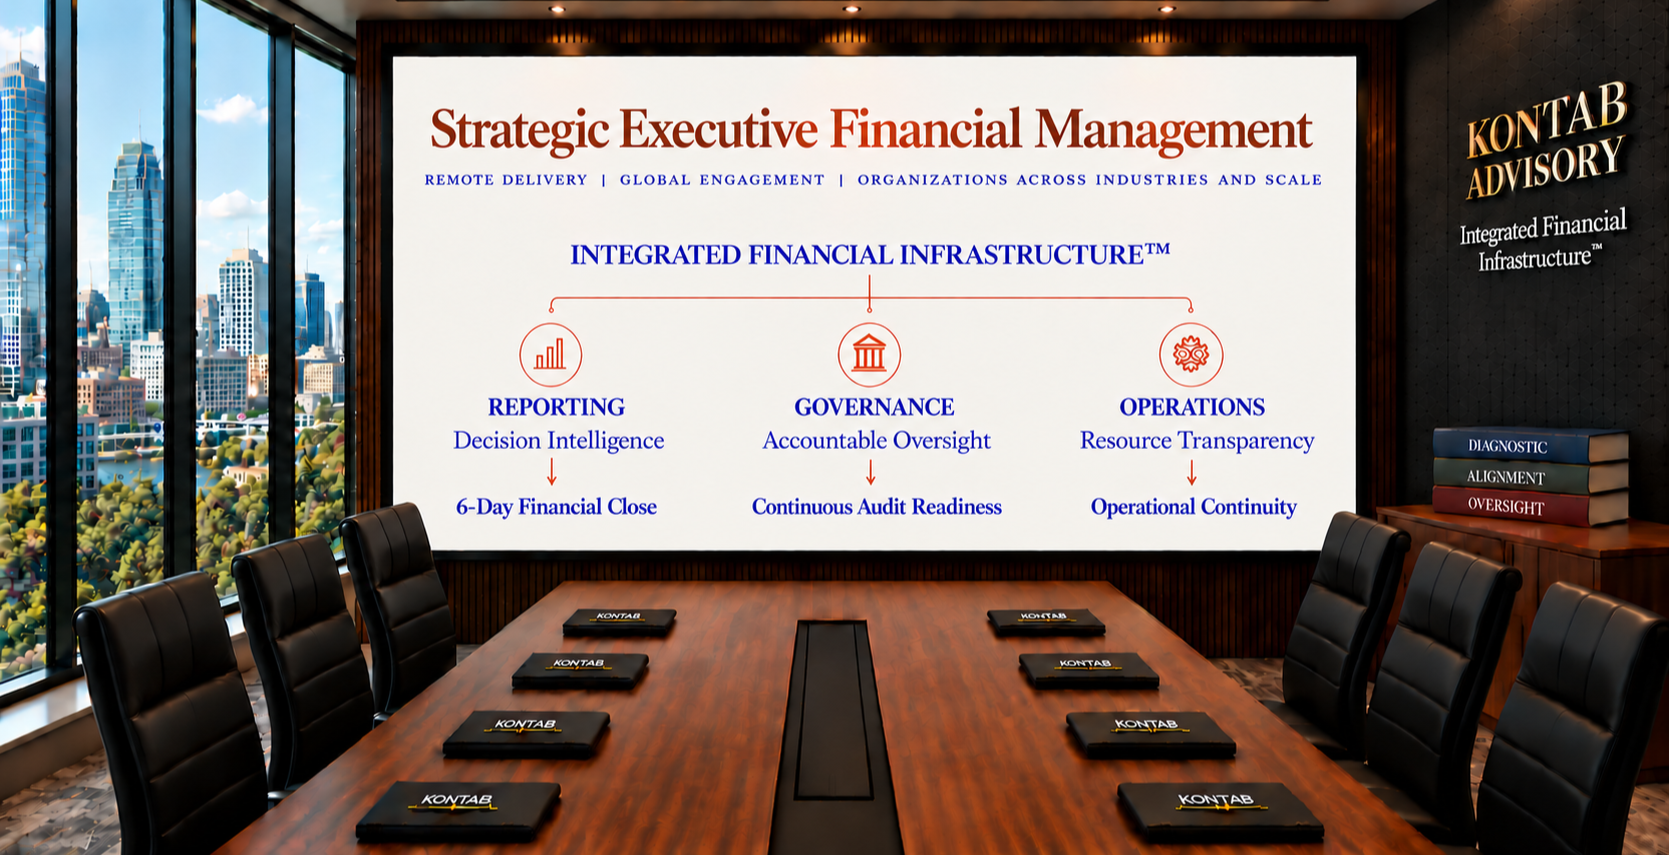
Reporting, governance, and operations perform distinct responsibilities within one financial environment. Their effectiveness depends on their relationships.
Reporting: Connects financial information with planning, performance analysis, and executive decision support.
Governance: Establishes authority, controls, responsibilities, and oversight.
Operations: Execute transactions, coordinate resources, maintain workflows, and support continuity.
Reliable reporting requires complete and appropriately recorded activity. Controls must operate where financial decisions and transactions occur. Operational procedures must support both execution and verification.
Alignment establishes these connections through defined responsibilities, consistent information, appropriate systems, and review procedures. It does not require one software platform or identical procedures across every activity. It requires arrangements that work together and preserve necessary distinctions.
Structural Alignment in Practice
Consider a vendor invoice. A coordinated workflow begins with receiving the invoice and required supporting information. The transaction is reviewed against relevant authorization, contract, budget, and funding requirements. A designated individual approves it within established authority.
The invoice then moves through accounting and payment procedures. Supporting records are retained, activity is reconciled, and the financial effect becomes available for reporting.
Exceptions require identified ownership throughout the process. This example is illustrative, not a universal configuration. Appropriate procedures depend on the organization and transaction.
Its significance is the connection among execution, authorization, records, reconciliation, and reporting. A transaction should not become disconnected from its supporting evidence or accountability as it moves between people and systems.
Evaluating Automation Readiness
Automation should support an understood process. Before implementation, determine whether:
Activities, inputs, outputs, and exceptions are defined.
Source information and classifications are reliable.
Authorization and review responsibilities are clear.
Appropriate validation and monitoring exist.
Configurations, maintenance, and continuity are documented.
Automation can reproduce incorrect rules as consistently as correct ones. It can also shift dependency from the person performing a process to the person maintaining its configuration.
Testing should include representative activity, unusual transactions, failures, and recovery procedures. Measure more than speed. Consider error rates, exception volumes, reconciliation differences, correction effort, and ongoing maintenance.
The appropriate objective is dependable execution with suitable controls, not automation for its own sake.
Sustainable scalability depends on whether financial responsibilities, controls, systems, and oversight remain coordinated as organizational requirements evolve. Infrastructure alignment establishes the conditions for that continuity; staffing and technology decisions should support those requirements rather than substitute for their evaluation.